HIGHLIGHTS
- Joby and Archer stocks decline despite nearing commercial air taxi launches, signaling investor concerns about profitability and operational scaling rather than technical readiness
- Market challenges include incomplete regulatory frameworks, uncertain insurance costs, battery limitations, and the heavy capital requirements for multi-city infrastructure deployment
- Future performance will depend on demonstrable operational execution, unit economics validation, and customer adoption metrics rather than regulatory approvals alone
The air taxi industry stands at a critical inflection point. After years of development, regulatory approvals, and infrastructure investment, companies like Joby Aviation and Archer Aviation are on the cusp of launching commercial air mobility services. Yet paradoxically, their stock prices are experiencing significant declines, raising questions about market sentiment, investor expectations, and the realities of scaling urban air mobility.
The Stock Decline Puzzle: Why Are Investors Selling?
Joby Aviation and Archer Aviation have both witnessed notable downward pressure on their share prices, even as their operational timelines accelerate toward commercial service launches. This counterintuitive market behavior suggests investors are grappling with concerns beyond simple product readiness. The selloff reflects deeper anxieties about profitability timelines, capital requirements, and competitive dynamics in the nascent air taxi sector.
Several factors may explain the bearish sentiment. First, the companies have burned significant capital during development phases, and investors may be questioning whether revenue generation can justify continued cash burn rates. Second, regulatory approval processes have proven more lengthy and costly than initially projected, extending time-to-profitability curves. Third, public markets are increasingly scrutinizing growth-at-all-costs narratives, demanding clearer paths to sustainable returns.
The timing is particularly sensitive because air taxi operations require heavy infrastructure investment—landing sites, charging infrastructure, air traffic management systems, and ground support facilities. These capital expenditures must be deployed across multiple cities simultaneously to achieve economies of scale, placing enormous pressure on balance sheets during the critical commercialization phase.
Joby Aviation’s Pathway to Launch
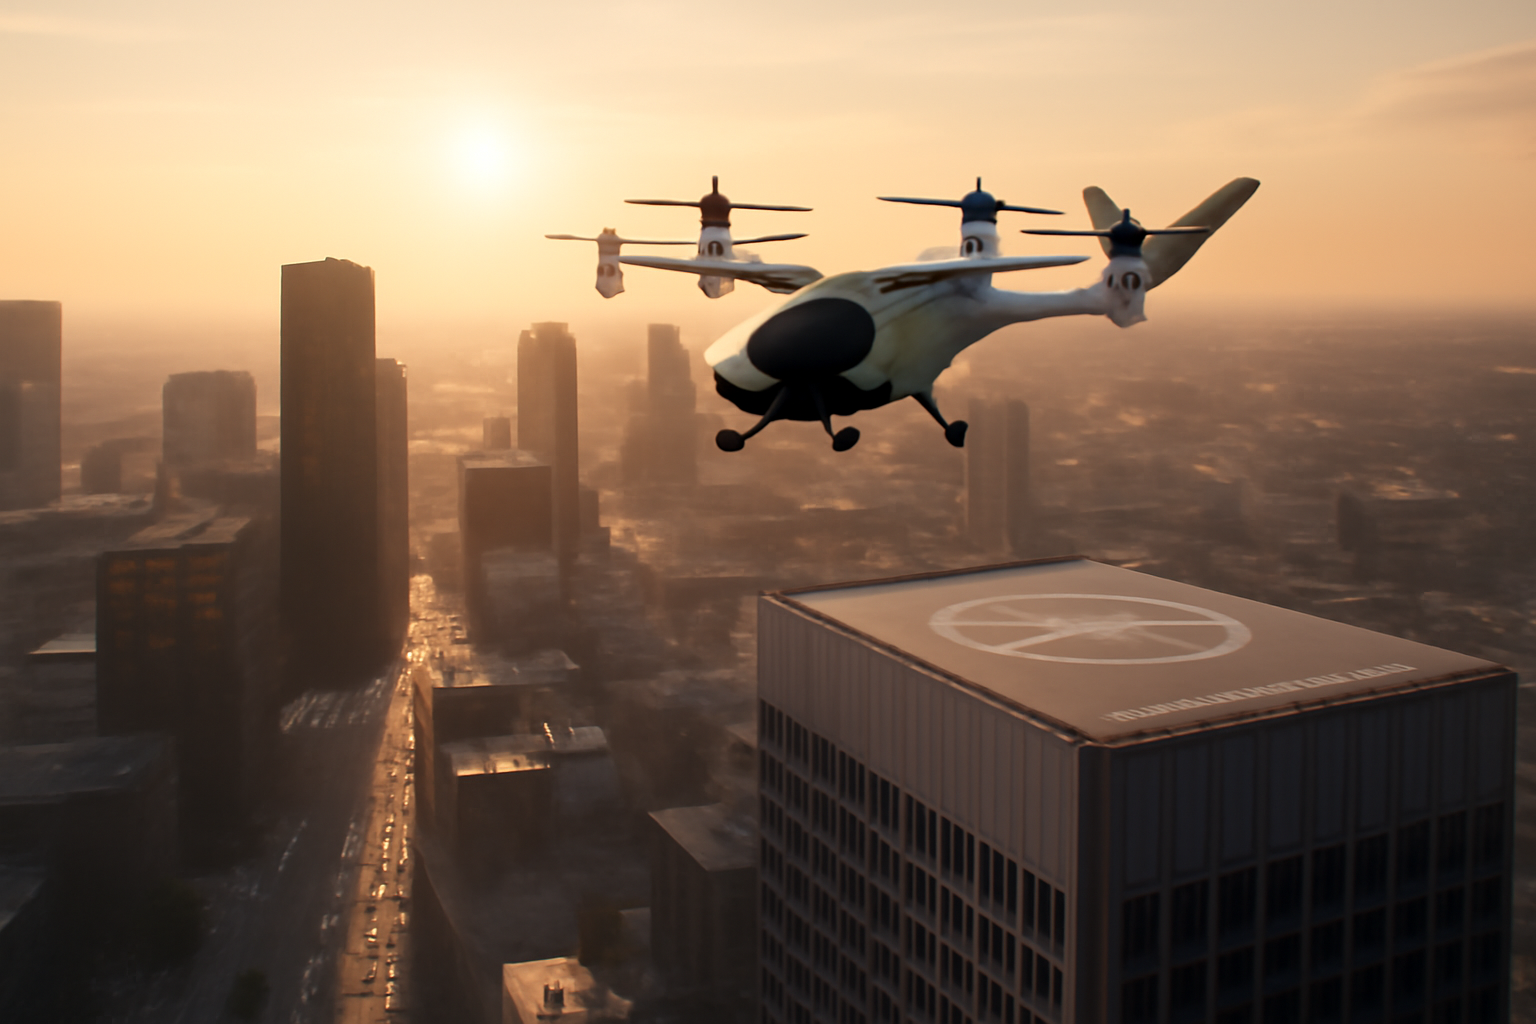
Joby Aviation remains one of the most advanced air taxi operators globally. The company has secured Federal Aviation Administration (FAA) approval for its electric vertical takeoff and landing (eVTOL) aircraft and has finalized operational plans for service launches in major metropolitan areas. Their aircraft represents years of engineering refinement, with emphasis on safety, noise reduction, and battery efficiency—critical factors for urban operations.
The company’s strategy focuses on premium, point-to-point urban mobility—initially targeting airport-to-city-center routes where high demand and established transportation hubs create optimal operational conditions. Joby’s partnerships with infrastructure providers and ground transportation operators are meant to create integrated mobility ecosystems. However, translating this strategic vision into profitable operations remains the core investor concern.
Stock volatility surrounding Joby likely reflects anxieties about whether the premium pricing model can sustain operations while building brand trust among early adopters. Additionally, any delays in obtaining final operational certificates or encountering technical issues during certification flights could trigger further downward pressure. The company’s success depends on flawless execution during this crucial commercialization window.
Archer Aviation’s Competitive Position
Archer Aviation has pursued a distinct operational strategy, targeting regional mobility corridors and potential launch markets with different competitive dynamics than Joby’s urban airport focus. The company’s aircraft design prioritizes manufacturing scalability and operational flexibility, potentially enabling faster expansion across multiple markets. This approach appeals to logistics and enterprise mobility use cases beyond traditional air taxi services.
Archer’s stock performance reflects similar macro concerns affecting the broader eVTOL sector: validation of demand assumptions, operational cost structures, and regulatory timelines. The company has demonstrated progress in securing regulatory certifications and establishing operational partnerships, yet investor sentiment remains tepid. This suggests that proximity to launch is not automatically translating into market confidence.
Competitive intensity in the air taxi space has also increased. Traditional aerospace companies, emerging Chinese manufacturers, and well-capitalized startups are all developing competing solutions. Investors may be discounting Joby and Archer valuations to account for intensifying competition and potential market share consolidation as the industry matures. First-mover advantages may be offset by later entrants with superior manufacturing capabilities or deeper pockets.
Market Realities and Industry Headwinds
The broader eVTOL market faces structural headwinds that extend beyond individual company execution. Regulatory frameworks remain incomplete across most jurisdictions, particularly regarding airspace management, pilot certification, and maintenance standards for electric aircraft. Insurance costs for new aviation categories remain uncertain, potentially impacting operational economics. Urban noise regulations, environmental impact assessments, and community acceptance all present unpredictable variables.
Battery technology, while advancing rapidly, still presents constraints on range, payload, and operational flexibility. Current generation eVTOL aircraft typically support 5-15 minute flights under ideal conditions—sufficient for many urban routes but limiting for broader regional mobility applications. The need for frequent charging, battery maintenance, and replacement creates ongoing operational costs that may pressure margins during the early commercialization phase.
Capital markets are also increasingly distinguishing between concept-stage companies and those approaching operations. Early-stage investors who entered at lower valuations during private funding rounds may be realizing gains, creating natural selling pressure. Conversely, new institutional investors assessing the sector may demand higher performance visibility before committing capital, resulting in weakened demand for public shares during this transition period.
Path Forward: Execution Over Narrative
For both Joby and Archer, near-term stock performance will likely depend less on regulatory progress and more on demonstrable operational execution. Successful service launches, positive customer adoption metrics, and evidence of sustainable unit economics will determine whether stock declines represent buying opportunities or genuine warnings about business model viability. Investors want to see revenue generation, customer retention, and clear paths to profitability.
The companies must also manage stakeholder expectations carefully. Overly optimistic projections about capacity utilization rates, passenger volumes, or profit margins will trigger sell-offs when reality proves more challenging. Conversely, transparent communication about challenges, realistic timeline projections, and conservative financial guidance can build investor credibility and stabilize valuations during commercialization phases.
Joby and Archer’s near-term success will also depend on achieving operational scale in their initial launch cities without catastrophic technical failures or safety incidents. Any accidents, regulatory violations, or service disruptions during early operations could severely damage brand reputation and investor confidence across the entire sector. The responsibility for careful, methodical scaling is enormous.
Key Takeaways for the Air Taxi Industry
- Stock declines reflect investor concerns about profitability timelines and operational scaling requirements, not technical readiness or regulatory approval progress
- Successful air taxi commercialization requires not just aircraft certification but also infrastructure deployment, regulatory frameworks, and sustainable unit economics across multiple cities
- Market maturation in eVTOL will ultimately separate companies with strong operational execution from those dependent on narrative momentum and investor sentiment
The paradox of Joby and Archer’s falling stock prices during their march toward operational launch reveals a fundamental truth about emerging mobility sectors: getting approval to operate is entirely different from building profitable, scalable businesses. Investors are pricing in the reality that the next phase—commercial operations—will be far more challenging than the development phase. Success requires not just great aircraft, but also operational excellence, cost control, and demonstrated customer demand. The coming months will be crucial in determining whether these companies can transform regulatory victories into business realities.