HIGHLIGHTS
- Beta Technologies posted a $119 million net loss in Q3 2026, reflecting typical pre-commercialization costs for eVTOL aircraft development and manufacturing infrastructure
- The company continues advancing toward FAA certification with successful test flights, positioning itself as a credible competitor in the competitive eVTOL marketplace
- Investor confidence will hinge on Beta’s ability to demonstrate progress toward certification and eventual revenue-generating commercial operations within its funding runway
Beta Technologies, one of the leading eVTOL developers in the personal air mobility sector, has reported a significant $119 million net loss for the third quarter of 2026. This financial announcement marks a critical milestone in the company’s journey, underscoring the substantial capital requirements and development costs associated with bringing electric vertical takeoff and landing aircraft to market. The loss highlights the ongoing challenges facing the eVTOL industry as companies race to achieve certification and commercialization while managing unprecedented R&D expenditures.
The Financial Reality of eVTOL Development
The $119 million quarterly net loss reported by Beta Technologies reflects the inherent costs of developing next-generation aviation technology. Unlike traditional aerospace companies with decades of established supply chains and manufacturing infrastructure, eVTOL startups must build their entire operational ecosystem from the ground up. This includes aircraft design and certification, battery technology development, charging infrastructure, pilot training programs, and regulatory navigation.
Beta Technologies’ financial position, while challenging, is not unique within the eVTOL sector. Companies like Joby Aviation, Archer Aviation, and Lilium have all reported substantial quarterly losses as they pursue FAA certification and scale manufacturing operations. The path to profitability in this industry requires sustained investment spanning multiple years, with most projections not expecting positive cash flow until well into the 2030s when commercial operations mature.
Investors and stakeholders must view these losses within the context of the company’s overall strategy and progress toward key milestones. Beta Technologies has demonstrated technical achievement with successful test flights and prototype development. The burning cash rate, while substantial, reflects aggressive investment in scaling operations and accelerating the timeline to market entry—a strategy that many investors view as necessary to capture early market advantage in the competitive eVTOL landscape.
Beta Technologies’ Path to Certification
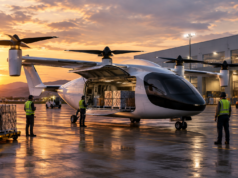
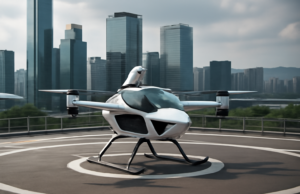
Beta Technologies has positioned itself as a serious contender in the eVTOL race through consistent technical progress and strategic partnerships. The company has conducted numerous test flights with its all-electric aircraft, demonstrating the viability of its propulsion and flight systems. These milestones are critical for building confidence with regulators at the Federal Aviation Administration and securing the special airworthiness certificates needed for commercial operations.
The company’s approach emphasizes practical, near-term applications for personal air mobility. Beta Technologies has focused on scenarios such as executive transport, medical evacuation, and point-to-point travel for time-sensitive missions. This targeted approach differs from some competitors pursuing broader urban air mobility networks, representing a strategic bet on near-term market opportunities while working toward longer-term transportation transformation.
Certification timelines remain a critical variable affecting the entire eVTOL sector. The FAA’s special conditions process for novel aircraft designs creates inherent uncertainty in development schedules. Beta Technologies’ substantial quarterly loss underscores the importance of maintaining investor confidence and capital availability throughout what could be a multi-year regulatory journey. The company’s ability to secure continued funding at favorable terms will largely determine whether it can sustain operations through eventual market entry.
Market Competition and Industry Dynamics
Beta Technologies operates within an increasingly crowded competitive landscape. Multiple well-funded startups, established aerospace firms, and international competitors are simultaneously pursuing eVTOL certification and commercialization. This competitive intensity raises the stakes for companies like Beta, which must demonstrate sufficient technical differentiation and market advantage to justify investor capital and secure its position as a market leader.
The quarterly loss also reflects Beta Technologies’ strategic decisions regarding manufacturing scale and supply chain development. The company has invested heavily in establishing production capabilities and securing long-term component contracts. These infrastructure investments represent necessary foundational costs that will only be recouped once aircraft enter service and generate revenue. Early market entrants with sufficient capital to sustain operations through certification benefit from first-mover advantages in pilot training, operator relationships, and market brand recognition.
Competitive dynamics in the eVTOL space are being shaped by differences in aircraft design philosophy, target markets, and business model strategies. Some companies emphasize maximum range and payload capacity, while others prioritize rapid certification timelines with more conservative specifications. Beta Technologies’ specific design choices and market positioning will ultimately determine whether the company’s current cash burn rate is justified by corresponding progress toward revenue-generating operations.
Investor Sentiment and Capital Availability
The announcement of Beta Technologies’ $119 million quarterly net loss will likely influence investor sentiment across the broader eVTOL sector. Capital markets have grown increasingly skeptical of high-burn-rate technology companies in recent years, particularly those lacking clear paths to near-term profitability. The eVTOL industry’s fundraising environment has tightened compared to the peak enthusiasm of 2021-2022, making significant quarterly losses more scrutinized by institutional investors.
However, the most sophisticated investors in the eVTOL space understand that substantial quarterly losses are inevitable during the development and pre-commercialization phases. The critical evaluation criterion is not the absolute loss figure but rather the progress achieved relative to capital deployed. If Beta Technologies demonstrates meaningful advancement toward certification and customer acquisition, large losses may be viewed as acceptable investments in future market opportunity. Conversely, if technical progress stalls or timelines slip significantly, investor patience will rapidly diminish.
Beta Technologies’ capital position and access to continued funding remain crucial variables affecting company viability. Well-capitalized startups with strong investor backing can weather extended pre-revenue phases, while undercapitalized competitors may face existential challenges. The company’s recent loss announcement will likely prompt increased scrutiny of the company’s funding runway and contingency plans. Transparent communication with investors about progress toward key milestones and revised cash flow projections will be essential for maintaining confidence during this critical development phase.
The Broader eVTOL Industry Outlook
Beta Technologies’ financial challenges are emblematic of broader structural issues affecting the eVTOL industry. The high capital requirements for aircraft development, coupled with regulatory uncertainty and protracted certification timelines, create substantial financial risk for early-stage companies. Unlike software or consumer electronics startups that can achieve profitability relatively quickly, aerospace companies require years of sustained investment before generating meaningful revenue.
Despite these challenges, industry analysts generally maintain bullish outlooks for long-term market potential. The fundamental value proposition of personal air mobility—speed, convenience, and reduced travel time for premium passengers and time-sensitive missions—remains compelling. Commercial applications in emergency medical services, executive transport, and urban congestion bypass represent near-term opportunities with defensible economics. As technology matures and manufacturing costs decline, broader market adoption could eventually drive scale and profitability.
Beta Technologies’ $119 million quarterly loss should be contextualized within multi-year development plans and long-term market opportunity assessments. The company’s technical progress, manufacturing investments, and regulatory pathway represent real assets and achievements that maintain strategic value even as quarterly results show substantial losses. The critical question for investors and industry observers is whether Beta Technologies will successfully navigate the certification and early commercialization phase to capture value from the emerging personal air mobility market.
Key Takeaways from Beta Technologies’ Q3 Financial Results
- Beta Technologies reported a $119 million net loss in Q3 2026, reflecting typical pre-commercialization costs for developing certified eVTOL aircraft and establishing manufacturing infrastructure
- The company continues advancing toward FAA certification with successful test flights and technical progress, positioning itself as a credible competitor in the crowded eVTOL marketplace
- Investor confidence in Beta Technologies will depend on demonstrable progress toward certification and revenue-generating operations, requiring transparent communication about funding runway and commercial timelines
Beta Technologies’ $119 million quarterly net loss represents a defining moment for the eVTOL startup, highlighting both the substantial capital requirements of the industry and the company’s commitment to aggressive development timelines. As the personal air mobility sector continues maturing, companies like Beta will face increasing pressure to demonstrate tangible progress toward certification and commercial operations. The coming months will be critical for Beta Technologies to maintain investor confidence and sustain the capital availability needed to reach this transformative inflection point.