
HIGHLIGHTS
- eVTOL market projected to experience explosive growth through 2035 with hundreds of billions in cumulative economic value across manufacturing, operations, and infrastructure development.
- Electric air taxis targeting commercial launch dates between 2026-2028, with early deployment focusing on high-value airport-to-downtown routes and congestion reduction in major metropolitan areas.
- FAA, EASA, and national aviation authorities actively developing certification standards and operational frameworks, with regulatory clarity accelerating manufacturer timelines and investor confidence in commercialization.
The electric vertical takeoff and landing (eVTOL) industry is poised for unprecedented expansion, with market projections indicating substantial growth through 2035. As regulatory frameworks mature and technological innovation accelerates, electric air taxis and urban air mobility solutions are transitioning from concept to commercial reality. This comprehensive market analysis explores the key drivers, challenges, and opportunities reshaping personal air transportation globally.
Market Growth Projections and Economic Impact
Industry forecasts predict the eVTOL market will experience explosive compound annual growth rates (CAGR) over the next decade, driven by increasing urbanization and congestion in major metropolitan areas. The shift toward sustainable transportation solutions is attracting significant venture capital and strategic investments from both aviation incumbents and technology-focused startups. Major aerospace manufacturers and automotive companies are establishing dedicated eVTOL divisions, signaling confidence in the market’s long-term viability.
Economic modeling suggests that widespread adoption of electric air taxis could generate hundreds of billions in cumulative value across manufacturing, operations, and infrastructure development. Cities investing in vertiport infrastructure and regulatory frameworks are positioning themselves as early leaders in this emerging transportation ecosystem. The potential for job creation spans engineering, manufacturing, operations, maintenance, and ground support services.
Price projections for point-to-point urban flights are expected to decline significantly as production scales and battery technology improves. Initial per-trip fares may range from $4-15 per mile, eventually approaching price parity with premium ground transportation options. This cost trajectory is critical for achieving the passenger volumes necessary to sustain profitable operations across multiple markets.
Electric Air Taxi Integration in Urban Environments
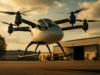
Electric air taxis represent the most commercially viable near-term application of eVTOL technology, with several manufacturers targeting operational launch dates between 2026 and 2028. These autonomous or piloted aircraft will connect city centers, airports, and suburban hubs, reducing commute times from hours to minutes. Urban air mobility networks require coordinated investment in vertiports, ground infrastructure, and air traffic management systems.
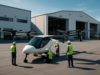
City planners and transportation authorities are beginning to incorporate air taxi corridors into master transportation plans, recognizing potential benefits for congestion reduction and emissions reduction. Partnerships between municipal governments, aviation authorities, and private operators are essential for successful integration. Early adopter cities in Asia, Europe, and North America are establishing regulatory sandboxes and infrastructure pilot programs to accelerate deployment.
Customer demand research indicates strong interest in air taxi services among time-conscious urban professionals and business travelers. Premium pricing models suggest initial markets will focus on high-value point-to-point routes, particularly airport-to-downtown connections. As fleet size expands and operational efficiency improves, service availability and affordability will expand to broader demographic segments.
Regulatory Framework Development and Certification Pathways
Regulatory agencies worldwide are actively developing certification standards and operational frameworks specifically tailored to eVTOL aircraft. The FAA, EASA, and national aviation authorities in key markets are establishing special conditions, acceptable means of compliance, and performance-based standards. This regulatory clarity is accelerating manufacturer development timelines and investor confidence in commercialization timelines.
Remote pilot licensing, air traffic integration, and safety verification protocols are being standardized to enable efficient scaling across multiple jurisdictions. International harmonization efforts aim to reduce certification complexity and enable global deployment of proven aircraft designs. Early regulatory decisions by leading aviation markets will establish precedents that influence global standards development.
Insurance frameworks, pilot training requirements, and passenger safety protocols are being established through collaboration between regulators, manufacturers, and insurance underwriters. The transition from manned to autonomous operations will require phased regulatory approval, with initial deployment emphasizing remote pilot oversight and redundant safety systems. Regulatory compliance will remain a critical cost factor throughout the 2026-2035 period.
Technological Innovation and Battery Technology Advancement
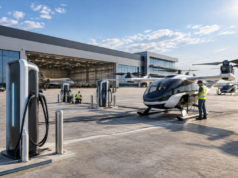
Battery energy density and charging infrastructure represent critical technical factors determining eVTOL market viability. Current lithium-ion battery technology enables 15-30 minute flight durations, sufficient for urban air taxi operations. Next-generation solid-state and alternative chemistry batteries under development could extend range and reduce weight, improving economics and operational flexibility significantly.
Electric propulsion architecture improvements, including distributed electric propulsion and hybrid-electric configurations, are increasing efficiency and payload capacity. Thermal management, power electronics, and motor technology advances are reducing system weight and cost while improving reliability. Noise reduction through advanced rotor designs and electric propulsion is addressing community concerns about vertiport operations in urban environments.
Autonomous flight systems, artificial intelligence-powered traffic management, and advanced materials are advancing rapidly through manufacturer R&D investments and university partnerships. Flight control algorithms, collision avoidance systems, and emergency response protocols are being validated through extensive simulation and testing programs. The integration of eVTOL operations into existing air traffic systems requires sophisticated ground-based and airborne coordination technologies.
Key Takeaways for Market Participants
- eVTOL market projections forecast substantial growth through 2035 as regulatory approval, technological maturity, and urban air mobility infrastructure accelerate commercialization timelines globally.
- Electric air taxi integration in major metropolitan areas is driving vertiport investment, battery technology advancement, and strategic partnerships among aerospace, automotive, and technology companies.
- Regulatory framework development by FAA, EASA, and national aviation authorities is establishing safety standards and operational procedures enabling efficient scaling across multiple jurisdictions and markets.
The convergence of regulatory clarity, technological maturation, and sustained investor commitment is positioning the eVTOL industry for transformative growth through 2035. Early adopter cities, experienced operators, and manufacturers achieving certification will establish competitive advantages in capturing market share across diverse geographic markets and customer segments. The transition from proof-of-concept demonstrations to profitable commercial operations represents the defining challenge and opportunity for the industry over the next decade.