HIGHLIGHTS
- FAA regulatory approval pathways are accelerating, with multiple manufacturers on track for certification within 12-24 months, reducing technical risk for investors
- Battery and electric drivetrain technology has matured beyond expectations, enabling 100+ mile ranges and 30-minute charge times for commercial operations
- First commercial eVTOL routes are launching in 2025-2026, creating revenue visibility for publicly traded manufacturers and potential wealth-building opportunities for early investors
The electric vertical takeoff and landing (eVTOL) industry is attracting unprecedented investor attention as the sector moves from concept to commercialization. With multiple companies preparing for certification and deployment of their aircraft, financial analysts are identifying potential wealth-building opportunities within this emerging market. The convergence of regulatory progress, technological maturity, and massive capital investment is creating a compelling case for investors seeking exposure to the future of urban air mobility.
The eVTOL Market Explosion
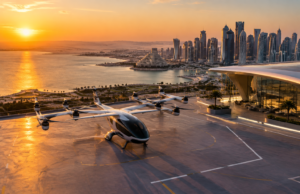
The global eVTOL market has grown from a speculative frontier to a sector with real commercial timelines. Major manufacturers including Joby Aviation, Lilium, Archer Aviation, and others have moved beyond prototype testing into advanced certification phases. These companies are now publicly traded or preparing to go public, giving investors direct access to equity positions in the emerging industry.
Market analysts project the eVTOL sector could be worth billions of dollars within the next decade as urban air mobility services launch in major metropolitan areas. The first commercial routes are expected to begin operation in 2025-2026, with several cities already designated as initial launch markets. This transition from development phase to revenue-generating operations represents a critical inflection point for investor returns.
The competitive landscape is intensifying as established aerospace companies, automotive manufacturers, and venture-backed startups all vie for market position. This dynamic creates multiple investment opportunities across different risk profiles and business models, from aircraft manufacturers to infrastructure providers and service operators.
Regulatory Breakthroughs and Certification Progress
The Federal Aviation Administration (FAA) has established a clear regulatory pathway for eVTOL aircraft certification, moving beyond experimental permits into Special Airworthiness Certificates. Multiple manufacturers have already demonstrated their aircraft to regulators and are on track for approval within the next 12-24 months. This regulatory clarity provides confidence that commercial operations are transitioning from “if” to “when.”
International regulators in Europe, Asia, and other regions are developing parallel certification frameworks that align with—while allowing for regional variations—U.S. standards. This global regulatory convergence accelerates the timeline for international market expansion and increases the addressable market for successful manufacturers. Companies with certifications valid across multiple regions gain significant competitive advantages.
The regulatory progress has direct financial implications for investors. Companies with advanced certification status show lower technical risk than those earlier in the development cycle. This tiered risk profile allows investors to choose between speculative high-growth plays and more established candidates approaching revenue generation.
Technology Maturation and Battery Breakthroughs
Battery technology has been the critical enabler for eVTOL viability, and recent advances have exceeded industry expectations. Energy density improvements, rapid charging capabilities, and thermal management solutions have all progressed faster than earlier projections. Several manufacturers now operate with ranges of 100+ miles and 30-minute charge times that make commercial route planning practical.
Beyond batteries, the broader technology stack supporting eVTOL operations has matured significantly. Electric powertrains are more efficient than initially modeled, noise levels are lower than anticipated, and redundancy systems meet or exceed aviation safety standards. These technical achievements reduce the risk profile for investors considering exposure to the sector.
Ongoing R&D investments promise further improvements in battery energy density, autonomous flight systems, and vehicle efficiency. Companies demonstrating tangible progress in these areas are positioned to capture market share as commercial operations scale. Investors should prioritize manufacturers with credible technology roadmaps and proven innovation pipelines.
Investment Pathways and Wealth Creation Potential
Direct equity investment in public eVTOL manufacturers offers the most direct exposure to sector growth. Companies that successfully achieve certification and launch commercial operations could see significant stock appreciation as revenue becomes visible. Early investors in companies that execute well on commercialization could see substantial returns as the market develops.
Beyond manufacturer equities, the eVTOL ecosystem includes infrastructure providers, battery suppliers, software platforms, and air traffic management systems companies. Diversified exposure across these segments reduces concentration risk while capturing the full value chain of the emerging industry. Some of these supporting companies may offer less volatile investment profiles than pure-play aircraft manufacturers.
Investment timing remains crucial in the eVTOL sector. Earlier-stage companies offer higher growth potential but greater technical and financial risk. More advanced candidates approaching certification and revenue offer lower risk but potentially moderate returns. A balanced portfolio approach across different development stages may optimize risk-adjusted returns for investors with appropriate risk tolerance and time horizons.
Key Investment Considerations
- Regulatory certification status and timeline are critical value drivers—prioritize companies with clear FAA or international approval pathways
- Battery technology and energy efficiency directly impact commercial viability and unit economics—monitor technical specifications and supplier relationships
- Pre-commercial partnerships with airlines, air taxi operators, or government agencies validate demand and reduce execution risk
The eVTOL sector represents one of the most significant transportation infrastructure shifts of the next decade. While all emerging technologies carry risk, the convergence of regulatory approval, technology maturation, and commercial deployment timelines suggests that early investors in successful companies could see substantial wealth creation. Investors should conduct thorough due diligence on individual companies’ technology, leadership, financial runway, and market partnerships—but the sector’s long-term opportunity appears compelling for those with appropriate investment horizons and risk tolerance.