HIGHLIGHTS
- China controls 80–90% of global NdFeB magnet production, creating existential supply chain risk for US EV drone and eVTOL manufacturers relying on electric motors.
- Domestic alternatives like Lynas Rare Earths and MP Materials won’t achieve meaningful production capacity until 2027–2028, leaving a 24–36 month vulnerability window.
- Leading manufacturers are adopting dual-sourcing strategies, strategic stockpiling, and design optimization to reduce magnet dependency and secure technological autonomy.
The electric vertical takeoff and landing (eVTOL) and EV drone industries face a critical vulnerability: dependence on China’s neodymium-iron-boron (NdFeB) magnet supply chain. As personal air mobility expands across North America and Europe, manufacturers scramble to secure rare earth materials essential for electric motors, power systems, and advanced flight control mechanisms. Without diversifying sourcing strategies, the US and allied nations risk supply chain disruptions that could delay commercial drone deployments, increase component costs, and compromise national security interests.
The NdFeB Magnet Crisis in EV Drone Manufacturing
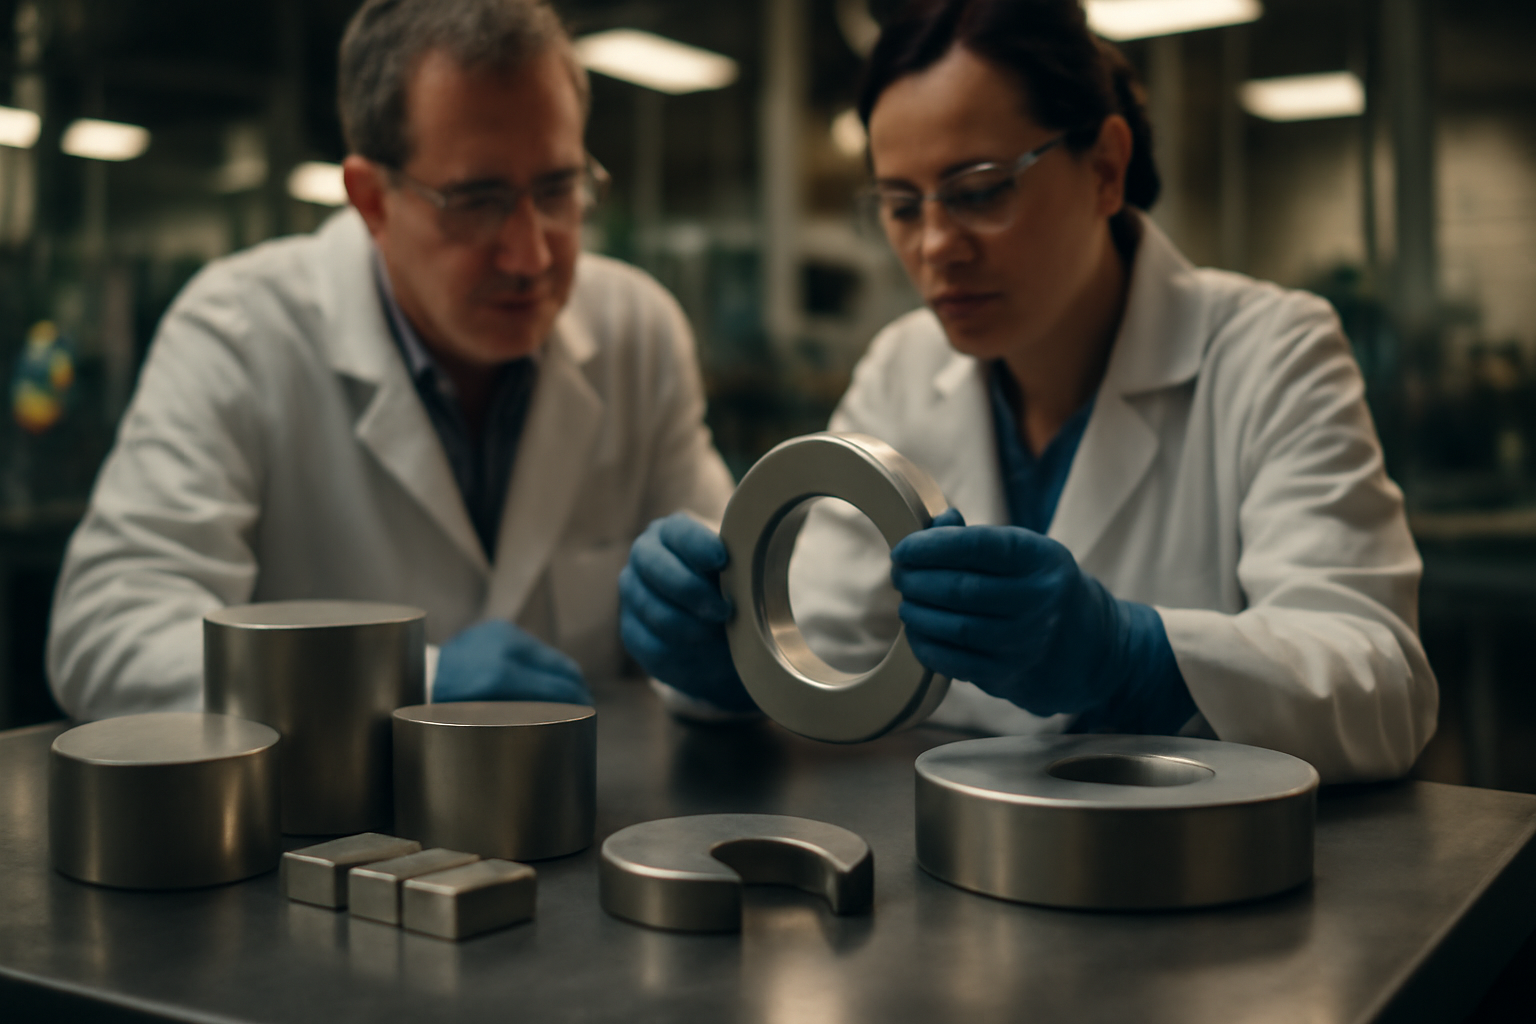
NdFeB magnets represent the backbone of modern electric propulsion systems. These permanent magnets—composed of neodymium, iron, and boron—generate the magnetic fields required for efficient electric motors used in drone rotors and eVTOL aircraft power plants. The performance advantages are undeniable: NdFeB magnets offer superior magnetic strength at minimal weight, a critical requirement for aerial vehicles where every gram impacts payload capacity and flight duration.
China currently controls approximately 80–90% of the global NdFeB magnet production capacity, along with dominant positions in rare earth element extraction and processing. This concentration reflects decades of investment in rare earth mining infrastructure, refining facilities, and magnet manufacturing expertise centered in provinces like Inner Mongolia and Shandong. US manufacturers of EV drones and eVTOL aircraft have few alternative suppliers, making them vulnerable to supply chain disruptions, export restrictions, or price volatility.
The implications are profound. A single geopolitical incident, trade dispute, or supply constraint in China cascades through the entire North American EV drone ecosystem. Companies racing to meet certification timelines, deliver pre-orders, or scale production can face months-long delays if magnet supplies are interrupted. This dependency threatens the US government’s ambitions to establish domestic advanced air mobility ecosystems and challenges private operators planning commercial drone delivery networks.
Rare Earth Supply Chain Fragmentation and Global Sourcing Challenges
Rare earth elements (REEs) required for NdFeB magnet production are geographically scattered but processing-concentrated. Neodymium and dysprosium deposits exist in the US, Canada, Australia, and other nations, yet China dominates the refining and separation of REEs into battery-grade and magnet-grade materials. This two-tier fragmentation means US mining companies cannot independently convert extracted ores into finished magnets without access to Chinese processing technology or facilities.
International supply chains are attempting to address this gap. Lynas Rare Earths, an Australian producer, has invested in US processing facilities. Mountain Pass in California, operated by MP Materials, represents a partial domestic production answer. However, these initiatives remain early-stage and insufficient to replace China’s mature, cost-competitive manufacturing base. Even as US government incentives and defense contracts push domestic capacity expansion, timelines stretch to 2027–2028 before meaningful volume substitution becomes possible.
Secondary refining channels—recovering rare earth materials from recycled electronics and end-of-life EV batteries—show promise but remain commercially immature. EV drone manufacturers cannot rely on recycled material streams today, forcing them to depend on primary (newly mined) supplies channeled through Chinese processing monopolies. This structural mismatch between supply diversification efforts and near-term manufacturing demand creates a critical window of vulnerability for the eVTOL industry.
National Security and Technological Autonomy Implications
The US military and defense contractors recognize the strategic risk. Autonomous drones, swarming systems, and advanced surveillance aircraft rely on high-performance electric motors powered by premium NdFeB magnets. Supply chain dependence on a strategic competitor undermines technological sovereignty and operational readiness. If geopolitical tensions escalate or China implements export controls targeting aviation-grade magnets, US military and commercial programs face immediate capability gaps.
Recent legislative responses include the Rare Earths and Critical Minerals Revitalization (RECMR) Act and defense budget allocations aimed at incentivizing domestic mining and processing. The Department of Defense has classified NdFeB magnets as a critical material requiring domestic stockpiling and source diversification. However, legislative timelines and commercial incentives move slower than supply chain vulnerabilities accumulate. Companies investing in EV drone manufacturing today cannot wait years for government-backed supply chain maturation.
Export control scenarios pose an additional risk. If China restricts magnet exports to US drone manufacturers as a retaliatory trade measure—a precedent established during past rare earth export restrictions—the eVTOL industry could face production halts. Unlike aerospace components governed by international agreements, rare earth magnets lack secure multinational supply guarantees, leaving manufacturers exposed to unilateral disruption.
Industry Adaptation Strategies and Long-Term Solutions
Forward-thinking EV drone manufacturers are pursuing multiple mitigation strategies. Some are stockpiling NdFeB magnets and finished propulsion systems to buffer against supply interruptions. Others are investing directly in domestic magnet manufacturing partnerships or acquiring minority stakes in alternative suppliers like Lynas or MP Materials. Advanced design approaches—such as magnet-optimization algorithms that reduce magnet mass per motor while maintaining performance—lower material intensity and expand sourcing flexibility.
Materials science innovation offers longer-term relief. Research into rare-earth-free permanent magnets, including samarium-cobalt alternatives and emerging soft magnetic composite technologies, could reduce dependence on neodymium over the next 5–10 years. Universities and government laboratories are accelerating these programs, but commercialization timelines remain uncertain. EV drone manufacturers cannot assume breakthrough materials will arrive before scale-up production begins in 2027–2029.
Supply chain transparency and strategic partnerships are emerging as best practices. Companies joining consortiums like the Advanced Battery Consortium or industry groups focused on critical minerals resilience gain visibility into alternative sourcing channels and early warnings of supply disruptions. Long-term contracts with Lynas, MP Materials, and emerging Southeast Asian processors—while more expensive than Chinese alternatives—provide hedging against geopolitical shocks. Forward-looking manufacturers accept modest cost premiums today to secure supply autonomy tomorrow.
Key Industry Takeaways
- China controls 80–90% of global NdFeB magnet capacity, creating critical vulnerability for US EV drone manufacturers dependent on reliable motor and propulsion systems.
- Domestic alternatives like Lynas and MP Materials face multi-year timelines to achieve meaningful volume, leaving the industry exposed to supply disruptions through 2027–2028.
- Defense contractors and commercial manufacturers are implementing dual-sourcing strategies, strategic stockpiling, and design innovations to reduce magnet intensity and secure technological autonomy.
The US EV drone and eVTOL industries stand at a critical juncture. Supply chain diversification from China’s rare earth magnet monopoly is not optional—it is existential. While government initiatives and alternative suppliers gradually mature, the next 24–36 months represent a vulnerability window where geopolitical shocks or supply disruptions could cascade through commercial air mobility programs. Manufacturers that act decisively today to secure alternative magnet sources, optimize designs, and build strategic partnerships will lead the next generation of autonomous aerial systems. Those that delay risk obsolescence and operational dependency on a strategic competitor.