HIGHLIGHTS
- From 1,200+ eVTOL proposals just two years ago, the industry is now consolidating around proven designs reaching certification and commercial operation milestones.
- Leading operators like Joby Aviation and Archer are preparing scheduled air taxi services in major cities, transitioning from development phase to revenue operations.
- Infrastructure, regulatory approval, and insurance frameworks are now the critical success factors—technology development is no longer the primary bottleneck.
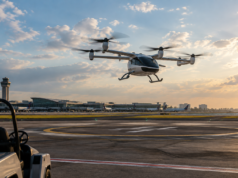
For years, the electric vertical takeoff and landing (eVTOL) industry has been a landscape of promises, prototypes, and speculative concepts. Two years ago, industry observers counted over 1,200 different eVTOL proposals—a staggering number that reflected both visionary optimism and considerable fragmentation. Today, as we head toward late 2026, that conversation has fundamentally shifted. The air taxi industry has moved from the question “Will this happen?” to the far more pressing question “What happens next?” This inflection point marks a critical transition from development-stage dreamware to genuine operational infrastructure.
The Great Consolidation: From 1,200 Concepts to Viable Operators
The sheer number of eVTOL proposals circulating two years ago represented both the industry’s infectious optimism and its lack of discipline. Dozens of startups, aerospace companies, and well-funded ventures were all working on solutions to the same fundamental problem: how to safely, economically, and sustainably transport passengers point-to-point within urban and regional airspace. That proliferation reflected investor confidence, regulatory interest, and genuine technological progress—but it also created enormous noise in the market.
Today’s landscape looks dramatically different. The viable operators have begun to separate from the also-rans, and the reasons are both encouraging and sobering. Companies like Joby Aviation, Archer Aviation, Lilium, and EHang have each achieved critical milestones that the broader pack has not: they’ve received advanced or final air worthiness certifications from regulators, they’ve demonstrated safe and reliable flight operations through extensive testing programs, and they’ve secured partnerships with real transportation operators and infrastructure providers. These are not minor achievements; they represent billions of dollars in capital investment, thousands of engineering hours, and genuine regulatory respect earned through demonstrated competence.
The consolidation reflects market realities that were always going to apply. Not every design will work at scale. Not every team has the engineering depth, financial runway, or strategic positioning to reach certification and commercial operation. The 1,200 proposals of two years past were never all going to survive; the current moment of industry convergence around a smaller number of credible actors was mathematically inevitable and economically healthy.
Regulatory Approval: From Barriers to Blueprints
One of the most significant shifts in the past 24 months has been the evolution of regulatory pathways. Two years ago, many observers viewed regulatory bodies—the FAA in the United States, EASA in Europe, and CAAC in China—as the primary unknown. Would they even permit eVTOL operations in populated areas? How conservative would their requirements be? Would the certification process stretch on for a decade, stalling the entire industry?
Those questions have not been fully answered, but meaningful progress has replaced uncertainty. The FAA’s grant of special airworthiness certificates to several eVTOL manufacturers, combined with the agency’s continued engagement with the industry on operational guidelines, has provided enough clarity that operators can now plan real launch timelines. The regulatory framework is becoming clearer, and while it remains demanding—rightfully so—it is no longer opaque. Companies are designing their aircraft and operational procedures to meet known regulatory standards rather than speculating about what those standards might demand.
Europe and Asia are moving in parallel, with their own regulatory timelines and approvals advancing. The EASA’s engagement with European eVTOL designers and the rapid advancement of certification work for models like the Lilium Jet demonstrates that international regulatory acceptance is a realistic near-term prospect. Regulators around the world have shifted from “Can we certify these vehicles?” to “How do we certify these vehicles in a way that maintains safety while enabling the innovation?”
The approval phase has also revealed important operational constraints and design requirements. Real-world regulatory scrutiny has pushed manufacturers to improve battery management, redundancy systems, noise mitigation, and ground infrastructure compatibility. These demands have been challenging, but they’ve also weeded out marginal designs and strengthened the survivors—a classic and healthy outcome of regulatory maturation.
Infrastructure and Operations: The New Bottleneck
With technology advancing and regulatory pathways clarifying, the industry’s focus has shifted decisively toward infrastructure and operational planning. This is a profound pivot. Building an air taxi network is not primarily an engineering challenge anymore; it is a logistics, real estate, and operational challenge.
The rooftop vertiports, ground-level landing zones, charging infrastructure, maintenance facilities, and traffic management systems that will enable commercial eVTOL operations require capital investment, urban planning coordination, and partnership with real-world transportation networks. These are immense undertakings. Consider Joby Aviation’s partnerships with major airport operators and transportation authorities, or Archer’s focus on integrating air taxi services into existing urban transportation systems—these represent a maturation of thinking about how eVTOLs actually fit into cities and transportation networks.
Operational complexity is also more understood now than it was two years ago. How do you schedule air taxi flights? How do you ensure safety in congested airspace? How do you train and certify pilots? How do you manage passenger demand and pricing? How do you integrate with ground transportation? These questions are no longer theoretical—they are being addressed in detail by operators who are preparing for actual service launches. The transition from “Can we fly these?” to “How do we operate these reliably and profitably?” represents genuine progress.
Infrastructure investment is also proceeding at a meaningful scale. Major cities are now actively planning for eVTOL integration into their transportation ecosystems. Partnerships between manufacturers, airport operators, and urban mobility providers are moving from concept to execution. This infrastructure wave is essential; without it, eVTOL vehicles remain curiosities rather than transportation solutions.
Safety, Insurance, and Passenger Confidence
One of the most underappreciated shifts in the eVTOL landscape is the maturation of safety protocols and insurance frameworks. Two years ago, these topics were speculative. Today, they are becoming concrete. Insurance underwriters, liability frameworks, and safety certification systems are being developed in parallel with aircraft development.
The early operational trials now underway provide invaluable safety data. Every test flight, every controlled operation, every near-miss or resolved technical issue contributes to the safety record and operational knowledge base that will underpin commercial service. As these records accumulate, passenger confidence and regulatory comfort both increase. Insurance premiums are already beginning to reflect demonstrated operational safety, which provides a positive feedback loop for operators who execute reliably.
Safety redundancy has also become increasingly sophisticated. Modern eVTOL designs incorporate multiple independent systems for propulsion, control, and emergency recovery. Battery management systems are far more robust than they were even two years ago. Fail-safe emergency landing procedures are being tested and refined. This relentless focus on safety is not just regulatory requirement; it is existential necessity for an industry that must build public trust to succeed.
The development of standardized procedures for pilot training, maintenance protocols, and operational safety is also advancing rapidly. These standards will be critical to scaling operations beyond a handful of pioneering routes. They represent the transition from experimental operations to genuinely scheduled, high-frequency service.
Key Operational Readiness Factors
- Regulatory certifications and approvals now provide clear technical and operational requirements rather than regulatory uncertainty
- Infrastructure partnerships with airports, cities, and transportation authorities are moving from planning to capital deployment
- Safety protocols, insurance frameworks, and pilot training standards are being developed in parallel with aircraft operations
- Demand modeling and revenue projections are increasingly grounded in real market research and confirmed partnerships rather than speculation
- Battery technology and charging infrastructure are advancing to support multiple daily operations per aircraft
As air taxis begin to actually take off, the narrative around eVTOL technology has matured dramatically. Two years ago, the industry faced legitimate questions about technological feasibility, regulatory acceptance, and market viability. Today, those questions have largely been answered affirmatively—at least for the leading operators and their proven designs. The new questions are operational and infrastructural: How quickly can cities build the necessary vertiport and charging ecosystems? How will pricing evolve as services scale? How will air taxi services integrate with existing urban transportation networks?
These are harder questions in some ways than the technology questions were. They require coordination across public and private sectors, real capital investment in fixed infrastructure, and genuine operational expertise. They also require sustained regulatory oversight and public confidence. But they are the kinds of questions that industries ask when they are transitioning from development to deployment. The air taxi industry is now in that transition. What we expect is not revolutionary technology announcements but steady, methodical progress toward safe, reliable, economically viable urban air mobility. That steady progress is finally beginning to materialize.