HIGHLIGHTS
- Archer Aviation (ACHR) stock is down 43% in 2026, raising questions about whether the company has reached a market bottom amid regulatory delays and manufacturing challenges
- FAA certification progress, production readiness milestones, and major customer partnerships will be critical catalysts determining if investor confidence can be restored
- Intensifying competition from well-funded eVTOL rivals and broader economic uncertainty have eroded Archer’s first-mover advantage and compressed near-term revenue prospects
Archer Aviation, one of the most closely watched players in the electric vertical takeoff and landing (eVTOL) space, continues to face significant headwinds in 2026. With the company’s stock (ticker: ACHR) down 43% year-to-date, investors are asking tough questions about the path forward and whether the market has finally priced in worst-case scenarios. As the aviation industry grapples with regulatory delays, manufacturing challenges, and competitive pressures, Archer’s steep decline raises critical questions about investor sentiment, the company’s operational trajectory, and the broader eVTOL market’s maturity.
The Reality of Archer Aviation’s 2026 Performance
Archer Aviation’s 43% decline in 2026 represents one of the most significant selloffs among publicly traded eVTOL manufacturers. This dramatic drop reflects investor concerns that extend far beyond typical market volatility. The company, which went public via SPAC merger in 2021 with significant fanfare, has struggled to meet the ambitious timelines and milestones that initial investors anticipated. Production delays, regulatory setbacks, and competition from well-capitalized rivals have all contributed to the stock’s underperformance.
The timing of this decline is particularly noteworthy given the broader economic environment and regulatory landscape surrounding personal air mobility. While some eVTOL companies have managed to maintain investor confidence through strategic partnerships or regulatory progress, Archer has found itself battling skepticism about its ability to achieve commercialization targets. The market has grown increasingly impatient with the company’s execution, and each quarter’s results—or lack thereof—has further eroded investor confidence.
Comparing Archer’s performance to peers reveals an industry-wide struggle, though ACHR’s decline exceeds many competitors. This relative weakness suggests that market participants have specific concerns about Archer’s technology, certification pathway, or business model that differentiate its outlook from other eVTOL developers. Understanding these distinctions is crucial for evaluating whether the stock has truly bottomed or if further downside remains.
Key Factors Driving the Stock Decline
Multiple structural and operational challenges have contributed to Archer’s steep slide throughout 2026. Regulatory delays in obtaining Special Airworthiness Certificates (SAC) and eventual Type Certification from the FAA have pushed back anticipated revenue milestones. The company’s original timelines for commercial operations have repeatedly slipped, causing investors to question management’s execution capabilities and the realism of remaining guidance.
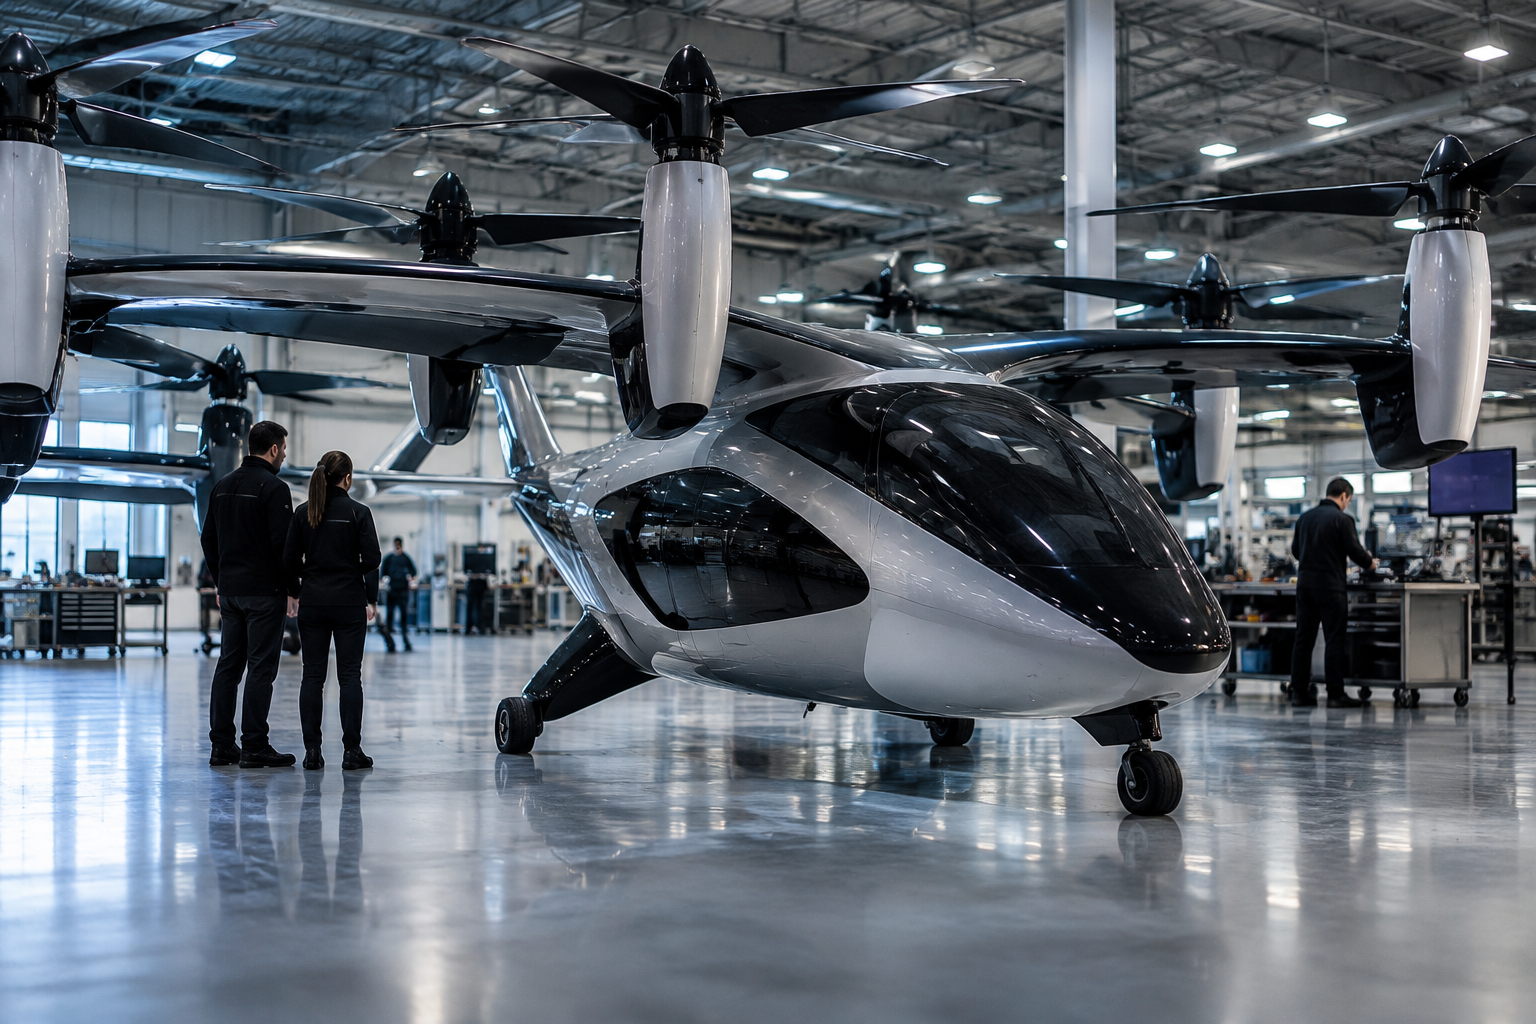
Manufacturing and supply chain obstacles have also plagued Archer’s progress. Scaling production of complex aerospace components while maintaining safety and quality standards has proven more difficult and expensive than anticipated. Battery technology limitations, in particular, have created range and payload constraints that complicate the company’s initial market positioning. These technical hurdles are not unique to Archer, but the market appears to be penalizing the company more severely than some competitors for each setback.
Competition from well-funded rivals—including Joby Aviation, Lilium, Volocopter, and others—has intensified throughout 2026. As multiple companies compete for the same regulatory approvals, pilot talent, and initial customer contracts, Archer’s first-mover advantage has diminished. Additionally, economic uncertainty and corporate travel budget constraints have reduced demand from potential early customers, further dampening investor enthusiasm for the sector’s near-term growth prospects.
What a Potential Bottom Might Look Like
Determining whether ACHR stock has truly found a bottom requires examining both technical and fundamental indicators. Technical analysts point to support levels and capitulation signals—such as extreme put-to-call ratios or insider buying activity—as potential markers of a bottom. If institutional investors or company insiders begin significant buying at current price levels, it could suggest that smart money believes the downside has been exhausted.
From a fundamental perspective, a bottom might be signaled by concrete progress on regulatory fronts, demonstrated manufacturing capability, or announced major partnerships or customer commitments. A major commercial agreement—such as an exclusive deal with a ride-hailing platform or significant pre-orders from a corporate customer—could materially change the narrative and restore investor confidence. Similarly, successful completion of critical certification milestones or proof of production readiness would validate the company’s path forward.
It’s also worth noting that sector-wide catalysts could impact whether Archer has truly bottomed. If regulatory frameworks for urban air mobility (UAM) accelerate or if corporate appetite for eVTOL services suddenly strengthens, rising tides could lift ACHR along with the entire market. Conversely, additional delays or negative regulatory developments could push the stock lower, suggesting that today’s prices do not yet represent true capitulation.
What Investors Should Watch Going Forward
As Archer Aviation navigates 2026’s challenges, several key metrics deserve close investor attention. Regulatory progress—particularly milestones related to Archer’s Maker aircraft certification—will be the primary driver of near-term stock performance. Any substantial movement toward FAA approval or expanded flight testing would likely provide meaningful upside relief. Quarterly cash burn rates and runway calculations are also critical; if the company’s cash position becomes precarious, it could force dilutive capital raises or strategic alternatives that harm shareholder value.
Customer commitment announcements will be essential to validating Archer’s business model. Early commercial partnerships, particularly with established transportation or logistics companies, would provide tangible evidence that demand exists at commercially viable price points. Additionally, production readiness data—factory capacity utilization, supply chain stability, and manufacturing cost trends—will help investors assess whether the company can eventually achieve profitability at scale.
Finally, competitive landscape changes deserve monitoring. Consolidation among eVTOL manufacturers, strategic pivots by competitors, or surprise regulatory approval for a rival platform could all impact Archer’s relative positioning. The eVTOL market remains highly dynamic, and unexpected developments can rapidly shift investor sentiment and stock valuations.
Key Takeaways for Investors
- Archer Aviation’s 43% stock decline in 2026 reflects deep investor concerns about regulatory delays, production challenges, and increased competition in the eVTOL space
- Whether ACHR has hit bottom depends on concrete progress in FAA certification, manufacturing readiness, and major customer commitments in coming quarters
- The broader eVTOL sector’s maturation and market consolidation will ultimately determine if Archer’s current valuation represents opportunity or indicates further downside risk
Archer Aviation’s 2026 stock performance has been punishing for shareholders, but whether it signals a bottom or portends further declines remains uncertain. The company’s success hinges on executing a complex roadmap involving regulatory approval, manufacturing scale-up, and customer acquisition—all while managing investor expectations and competing in an increasingly crowded market. For investors considering ACHR at current levels, the critical question is not whether the worst is behind us, but whether Archer possesses the operational excellence and market timing to justify recovery. The answers will become clearer as regulatory milestones approach and the company’s manufacturing capabilities are put to the test.