HIGHLIGHTS
- Embraer targets type certification and regulatory approvals across major aviation markets by 2027–2028, leveraging its established relationships with EASA, FAA, and ANAC.
- The company projects significant eVTOL revenue streams from aircraft sales, aftermarket services, flight operations software, and maintenance programs, diversifying income beyond unit sales.
- Strategic partnerships with battery manufacturers, infrastructure providers, and early-operator customers are central to Embraer’s commercialization strategy and cost-reduction roadmap.
Embraer, the Brazilian aerospace manufacturer, has provided fresh insights into its electric vertical takeoff and landing (eVTOL) program during its third-quarter 2026 earnings call. The company’s strategic pivot toward personal air mobility represents a significant expansion of its traditional commercial aviation business and signals growing confidence in the near-term commercialization of advanced air mobility (AAM) technologies. As regulatory frameworks mature and technological barriers continue to fall, Embraer’s participation underscores the industry-wide momentum toward urban air mobility solutions.
Embraer’s eVTOL Development Timeline and Milestones
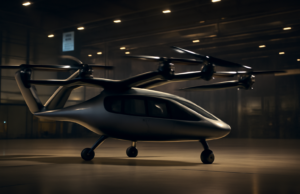
During the Q3 2026 earnings presentation, Embraer outlined its roadmap for bringing electric vertical takeoff aircraft to market. The company has invested significantly in R&D infrastructure and engineering talent to accelerate development cycles. This commitment reflects Embraer’s recognition that the AAM market window is rapidly opening, with first commercial operations expected across multiple regions within the next 2–3 years.
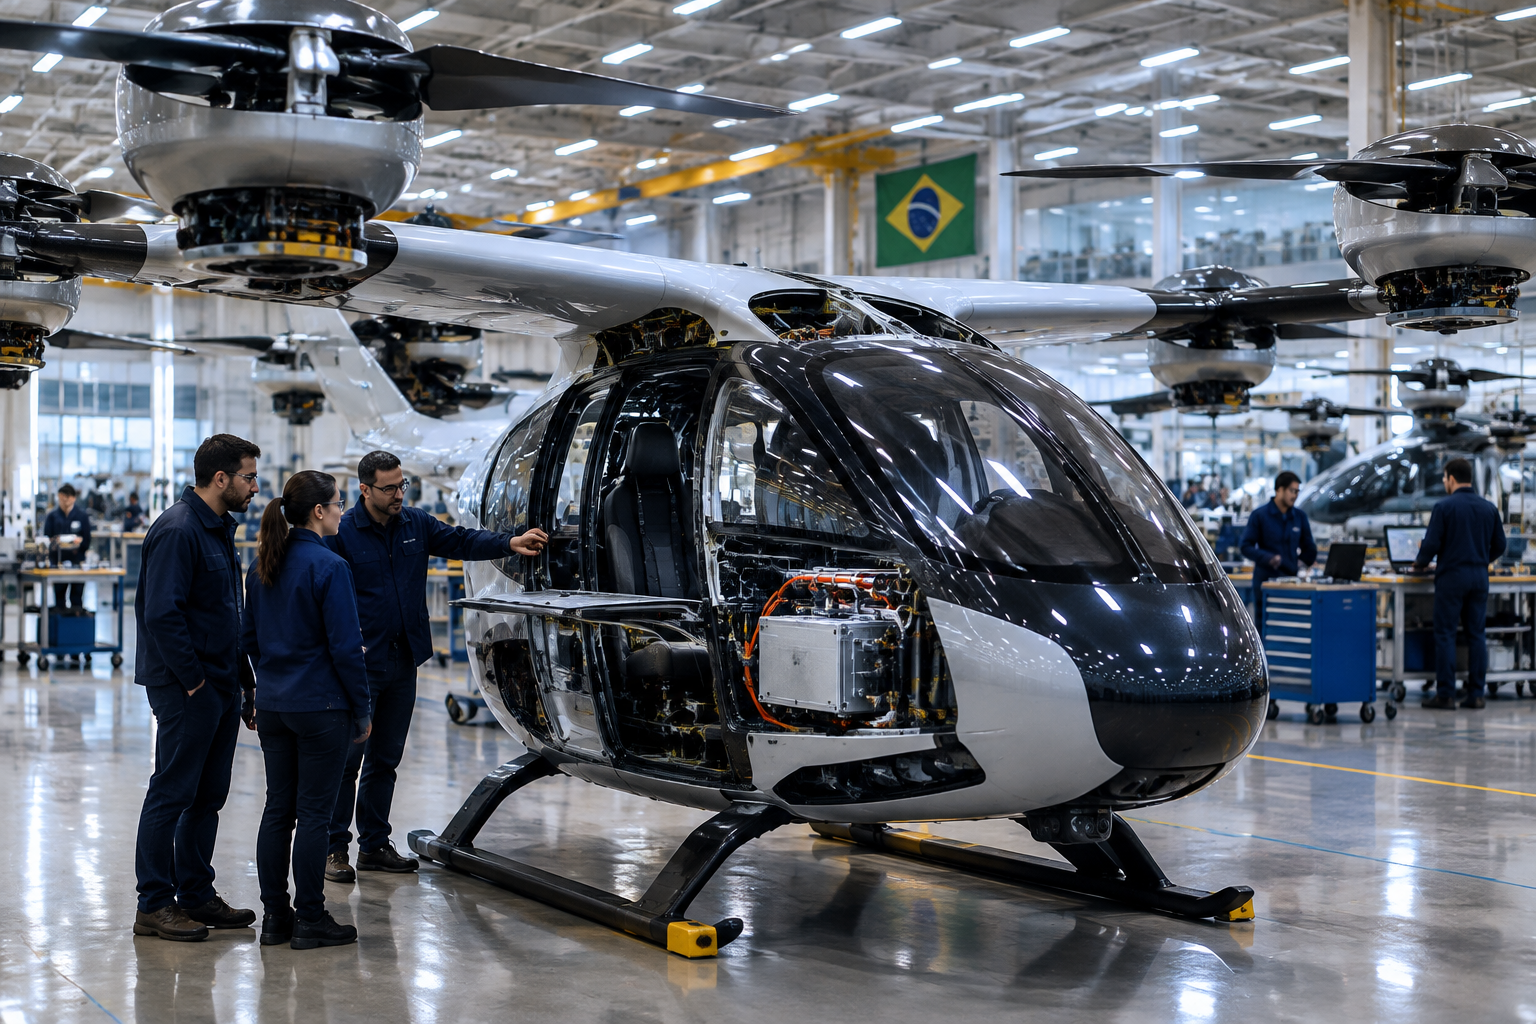
The company emphasized progress on critical subsystems, including battery technology integration, propulsion efficiency, and lightweight materials science. These technical achievements are essential foundations for achieving the range, payload, and reliability requirements demanded by commercial operators and regulators. Embraer’s legacy in aircraft certification and manufacturing quality control provides a competitive advantage as it transitions into the eVTOL space.
Investors and analysts took note of Embraer’s phased approach: initial focus on short-range urban routes, followed by expansion into regional corridors. This strategy aligns with anticipated regulatory clearance timelines and early customer demand patterns identified across key markets in the Americas, Europe, and Asia-Pacific.
Market Opportunities and Revenue Projections
Embraer’s earnings call highlighted substantial addressable market opportunities in urban and regional air mobility. The company projects significant revenue potential from both aircraft sales and aftermarket services, positioning eVTOL as a growth pillar for the next decade. Early customer interest from air taxi operators, regional airlines, and logistics companies has validated demand assumptions underlying the company’s business model.
The aerospace giant is evaluating multiple revenue streams beyond aircraft manufacturing: energy management solutions, flight operations software, pilot training, and maintenance programs. This vertical integration approach mirrors Embraer’s success in traditional commercial aviation, where ecosystem partnerships and service contracts drive long-term profitability. The diversified revenue model reduces dependency on aircraft unit sales alone and creates stickier customer relationships.
Geographic expansion planning received particular emphasis, with Embraer identifying priority markets based on regulatory maturity, urban density, and transportation infrastructure gaps. The company is actively engaging with government agencies, airport operators, and aviation authorities to shape favorable operating environments and secure early approvals for pilot programs and demonstration flights.
Regulatory Progress and Certification Strategy
A critical element of Embraer’s eVTOL strategy involves navigating the evolving regulatory landscape. The company reported ongoing collaboration with EASA (European Union Aviation Safety Agency), FAA (United States), and ANAC (Brazil’s National Civil Aviation Agency) to establish special conditions and certification pathways for eVTOL aircraft. These regulatory partnerships are accelerating the company’s ability to achieve type certification on realistic timelines.
Embraer highlighted its advantage as an established aerospace manufacturer with deep regulatory relationships and proven compliance track records. Unlike startup competitors lacking certification experience, Embraer can leverage institutional knowledge and existing approval processes to streamline the path to commercial operations. The company is investing in test facilities and simulation capabilities to support rigorous certification validation.
The company’s approach emphasizes safety-first principles consistent with its reputation in commercial aviation. Independent third-party validation, redundant systems architecture, and comprehensive failure analysis ensure that eVTOL aircraft meet or exceed existing general aviation safety standards. This commitment to regulatory rigor builds confidence among investors, operators, and potential passengers as the industry moves toward mass-market adoption.
Competitive Positioning and Strategic Partnerships
During Q3 2026, Embraer addressed its competitive position relative to specialized eVTOL startups and other aerospace incumbents. The company emphasized its manufacturing scale, supply chain maturity, and brand reputation as durable competitive advantages. While startups have demonstrated innovative designs and attracted venture capital, Embraer’s ability to achieve economies of scale and secure production financing provides structural advantages during the transition to commercial operations.
Strategic partnerships remain central to Embraer’s eVTOL strategy. The company is collaborating with technology providers, battery manufacturers, avionics suppliers, and potential operators to co-develop solutions tailored to market requirements. These partnerships accelerate innovation cycles and distribute technical risk across multiple stakeholders. Joint ventures and technology licensing arrangements extend Embraer’s reach into adjacent markets without requiring total internal investment.
The company is also engaging with infrastructure partners to address landing site requirements, charging networks, and ground support systems essential for commercial eVTOL operations. Embraer’s involvement in infrastructure planning positions it as a systems integrator rather than a pure-play aircraft manufacturer, creating additional value capture opportunities across the urban air mobility ecosystem.
Key Strategic Priorities for Embraer’s eVTOL Program
- Accelerate type certification and regulatory approvals with major aviation authorities across the Americas, Europe, and Asia-Pacific regions by 2027–2028.
- Establish strategic partnerships with battery suppliers, charging infrastructure providers, and early-operator customers to de-risk commercialization and secure revenue commitments.
- Invest in manufacturing infrastructure and supply chain capabilities to achieve production scalability and cost reduction targets essential for market competitiveness.
Embraer’s Q3 2026 earnings reveal a company methodically building the technological, regulatory, and commercial foundations required for successful eVTOL market entry. With operational excellence credentials, established aerospace relationships, and patient capital support, Embraer is positioning itself as a credible long-term player in the emerging personal air mobility ecosystem. As the industry transitions from development toward commercialization, Embraer’s structured approach and resource depth offer investors and operators the confidence that eVTOL operations will achieve scale and profitability within the decade. The aerospace industry’s participation in urban air mobility signals that this transition is no longer speculative—it is now a core business transformation for legacy aviation manufacturers.