HIGHLIGHTS
- Joby Aviation receives a buy rating from TipRanks investors due to its clear regulatory approvals and near-term commercialization pathway, while Archer Aviation’s longer timeline creates strategic uncertainty
- The eVTOL investment landscape is shifting from technology-driven valuation to execution-focused metrics, with regulatory progress and commercial partnerships becoming primary value drivers
- Diverging investor sentiment between the two companies signals potential industry consolidation, as competitors without transparent regulatory timelines face mounting pressure to merge or restructure
The personal air mobility sector is experiencing a critical inflection point, with investor sentiment increasingly differentiated between leading eVTOL manufacturers. A recent analysis from TipRanks has highlighted a notable divergence in the investment outlook for two of the industry’s most prominent publicly-traded players: Joby Aviation and Archer Aviation. This comparison underscores the mounting pressures and opportunities facing companies racing to commercialize electric vertical takeoff and landing technology at scale.
The Joby Aviation Investment Case: Building Momentum
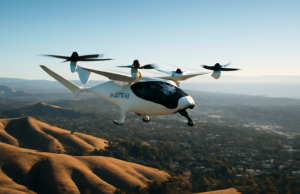
Joby Aviation has emerged as a frontrunner in the eVTOL sector, demonstrating substantial progress toward its commercialization goals. The company’s technical achievements, regulatory pathway clarity, and strategic partnerships have bolstered investor confidence in its ability to deliver near-term operations. With backing from prominent investors and a clear timeline for launching commercial air taxi services, Joby has positioned itself as a company with achievable near-term milestones.
The investor recommendation favoring Joby reflects confidence in the company’s execution capabilities and market timing. Joby’s aircraft design has undergone extensive testing, and the company has secured crucial approvals from aviation authorities. Additionally, partnerships with established operators and infrastructure providers have strengthened the company’s go-to-market strategy, demonstrating a comprehensive approach to deployment rather than merely relying on technological superiority.
Joby’s valuation relative to its development stage and de-risked operational pathway has attracted institutional investors seeking exposure to the personal air mobility market with reduced speculative risk. The company’s progress in obtaining operational approvals and establishing commercial service frameworks has solidified its position as a credible near-term player in urban air mobility.
Archer Aviation’s Unclear Path Forward
Archer Aviation, while technically innovative, faces a different investment narrative. The company’s longer development timeline, regulatory uncertainties, and less defined commercialization strategy have created ambiguity regarding its path to profitability and market relevance. Unlike Joby, which has clearly communicated operational timelines and secured regulatory pre-approvals, Archer’s regulatory status remains less transparent to investors.
The lack of clarity surrounding Archer’s certification pathway and commercial deployment schedule has created hesitation among institutional investors. Without clearly articulated milestones and regulatory approvals, the company operates under greater execution risk. The eVTOL sector’s highly competitive landscape means that delays in certification or commercialization can result in significant market share losses to competitors with more defined timelines.
Archer’s technology foundation remains sound, but the company’s investment case is hampered by communication challenges and an extended development horizon. Investors are increasingly risk-averse regarding companies with extended timelines and unresolved regulatory questions, particularly as faster-moving competitors demonstrate clearer paths to revenue generation.
Sector Dynamics and Competitive Pressure
The divergence between Joby and Archer reflects broader competitive dynamics reshaping the eVTOL industry. As regulatory frameworks become clearer and technical certification standards are established, companies demonstrating tangible progress toward these benchmarks receive premium valuations. The market is consolidating investor capital toward organizations demonstrating execution capability over technological promise alone.
Multiple eVTOL manufacturers are competing for the same regulatory approvals, commercial partnerships, and venture capital funding. Companies that secure regulatory approvals early enjoy first-mover advantages in establishing air routes, training facilities, and passenger confidence. This winner-take-most dynamic has intensified scrutiny of each company’s regulatory status and timeline transparency.
The investment community is increasingly focused on de-risking their eVTOL exposure by backing companies with demonstrable progress toward specific, achievable milestones. Generic technological excellence no longer suffices; investors demand proof of regulatory engagement, commercial partnerships, and clear operational timelines. This shift rewards companies like Joby that have methodically advanced their regulatory approvals and public communication strategies.
Market Implications and Industry Consolidation
The investment recommendation differential between Joby and Archer signals potential consolidation within the eVTOL sector. Companies unable to clearly demonstrate regulatory progress or articulate credible commercialization timelines may face pressure to merge with better-positioned competitors or seek alternative capital structures. This represents a natural maturation phase as the industry transitions from speculative venture-stage companies to operationally-focused enterprises.
Investors monitoring the eVTOL sector should recognize that regulatory approval and commercialization clarity have become primary valuation drivers. Technical capabilities alone are insufficient to justify investment in this capital-intensive industry. Companies must demonstrate engagement with aviation authorities, secured partnerships with operational infrastructure providers, and realistic timelines for service launch.
The bifurcation of investor sentiment between Joby and Archer reflects market maturation and rational capital allocation. As eVTOL technology moves from theoretical to practical commercialization, the investment community increasingly rewards execution capability over R&D promise. This evolution should continue to shape sector valuation dynamics over the coming quarters.
Key Investment and Market Takeaways
- Joby Aviation’s clear regulatory pathway and near-term commercialization timeline have earned a buy rating, while Archer faces investor uncertainty due to less transparent certification progress and longer deployment horizons
- The eVTOL sector is consolidating capital toward companies demonstrating tangible regulatory approvals and operational partnership clarity, signaling a shift from technology promise to execution capability
- Investor differentiation between Joby and Archer suggests potential industry consolidation, as companies unable to articulate credible commercialization timelines may face mounting pressure to merge or restructure
The investment analysis comparing Joby Aviation and Archer Aviation reflects the maturing eVTOL sector’s shift toward rewarding regulatory execution and commercialization clarity. As personal air mobility technology approaches practical deployment, investor capital will increasingly flow toward companies demonstrating tangible progress toward service launch rather than purely technical innovation. This dynamic will reshape competitive positioning, valuation metrics, and potentially trigger strategic consolidation within the industry.