
HIGHLIGHTS
- Archer Aviation’s stock has experienced a dramatic 50% decline, sparking investor debate about whether the downturn reflects market correction or fundamental business challenges.
- Industry experts question whether this valuation represents a buying opportunity or a warning sign about the eVTOL sector’s path to profitability and regulatory approval.
- Archer’s stock performance mirrors broader eVTOL market volatility as companies race to secure FAA certification and demonstrate commercial viability.
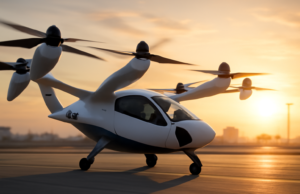
Archer Aviation, one of the most high-profile electric vertical takeoff and landing (eVTOL) companies in the race to commercialize personal air mobility, has seen its stock price plummet 50%, triggering intense debate among investors about whether this represents a genuine buying opportunity or a harbinger of deeper troubles within the nascent eVTOL sector. The dramatic decline has reignited questions about valuation expectations, path to profitability, and the timeline for regulatory certification—issues that will ultimately determine whether companies like Archer can deliver on their ambitious promises to transform urban transportation.
Understanding the 50% Stock Decline
The sharp drop in Archer Aviation’s stock price didn’t occur in isolation. Over the past 18 months, eVTOL companies across the board have faced headwinds from multiple directions: rising interest rates making capital-intensive aerospace ventures less attractive to investors, delays in FAA certification timelines, and a broader market correction in growth-stage technology stocks. Archer’s valuation has proven particularly vulnerable to shifts in investor sentiment, as the company remains pre-revenue and entirely dependent on securing both regulatory approval and customer commitments before it can generate meaningful income.
Market analysts have pointed to several specific catalysts for Archer’s recent decline. Competition in the eVTOL space has intensified significantly, with companies like Joby Aviation, Lilium, and Vertical Aerospace all pursuing similar certification pathways and customer bases. Additionally, supply chain constraints affecting aerospace manufacturing and persistent concerns about battery technology scalability have weighed on investor confidence across the sector. The company’s quarterly earnings reports and forward-looking guidance have also reflected more cautious timelines for commercialization, pushing back revenue projections and profitability milestones.
For long-term investors in the eVTOL space, these corrections are often viewed through the lens of comparable historical precedents. The aerospace and aviation sectors have historically required decades and billions in capital before achieving profitability. Early-stage companies in transformative technologies frequently experience significant stock volatility as markets reconcile utopian visions with engineering realities and regulatory roadblocks. Archer’s 50% decline, while stark, must be contextualized within broader sector trends and the company’s specific progress toward its stated milestones.
The Bull Case: Why This Might Be a Buying Opportunity
Proponents of Archer Aviation argue that the company’s 50% stock decline represents an overcorrection driven more by market sentiment and short-term trading dynamics than by fundamental changes to the company’s business prospects. Archer has secured significant partnerships, including agreements with United Airlines for potential commercial routes and relationships with major aerospace suppliers that validate the company’s engineering approach. The company’s regulatory trajectory remains on track, with ongoing development and testing progress that positions it well for FAA certification within the next 24 to 36 months.
Archer’s leadership team brings extensive experience from established aerospace and aviation companies, distinguishing it from some competitors who lack deep industry expertise. The company has also demonstrated technical achievements in propulsion systems and aircraft design that have impressed industry observers and regulatory bodies. For investors with a multi-decade time horizon, the argument goes, Archer’s current valuation might represent an entry point before the company completes certification and begins generating revenue from commercial operations and air taxi services.
The addressable market for eVTOL air mobility remains enormous. Investment banks and consulting firms have projected that urban air mobility could generate hundreds of billions in annual revenue within 15 to 20 years, assuming regulatory frameworks stabilize and manufacturing costs decline as production scales. Archer is positioned in what many believe will be a high-growth segment, with brand recognition, customer commitments, and technological differentiation that could justify substantially higher valuations once commercialization begins. From this perspective, a 50% decline simply resets valuations to more reasonable levels and creates an asymmetric risk-reward for patient capital.
The Bear Case: Signals of Fundamental Trouble
Skeptics of Archer Aviation contend that the 50% stock decline reflects genuine concerns about the company’s path to profitability and the viability of the eVTOL business model itself. The regulatory approval process for advanced air mobility remains uncertain and potentially prolonged. The FAA has been cautious in its approach to certification, requiring extensive testing and validation protocols that could extend timelines well beyond current company guidance. Any regulatory setback or requirement for substantial design modifications could significantly impact Archer’s commercialization timeline and capital requirements.
Cost considerations also loom large in the bear case. Current projections suggest that early eVTOL air taxi rides will cost hundreds of dollars per trip, far higher than traditional ground transportation. Achieving cost structures that attract mainstream consumers—rather than niche luxury markets—will require manufacturing scale that doesn’t yet exist and battery technology improvements that may be years away. If Archer and competitors cannot demonstrate a plausible pathway to affordable operations within the next 5 to 7 years, the entire market thesis could unravel, and investor capital currently deployed in the sector may never generate returns.
Additionally, capital requirements for certification, manufacturing facility construction, and fleet deployment will likely prove enormous. Archer has raised substantial sums, but many industry observers believe that the company and its competitors will need to return to capital markets multiple times before achieving profitability. In a high interest rate environment, this dilution cycle becomes increasingly painful for existing shareholders. The bear case argues that investors would be prudent to wait for more definitive proof of commercialization progress before deploying capital, rather than betting on potential recovery from an already-depressed valuation.
Sector Context and Competitive Dynamics
Archer Aviation’s stock performance cannot be divorced from the broader eVTOL sector’s current trajectory. Joby Aviation, Lilium, and Vertical Aerospace have all experienced significant stock declines in recent months, suggesting that the selloff reflects sector-wide skepticism rather than Archer-specific failures. This dynamic can be interpreted both ways: either the entire sector is oversold and presents opportunity, or systemic challenges affect all participants and individual company selection becomes critical to avoiding value destruction.
The competitive landscape has also intensified in unexpected ways. Established aerospace manufacturers like Boeing and Airbus have begun investing directly in eVTOL development or acquiring smaller competitors, potentially outmaneuvering pure-play eVTOL startups through superior capital resources and existing supply chain relationships. Strategic partnerships and consolidation could reshape the sector in ways that disadvantage companies like Archer, which has chosen to remain independent. Conversely, partnerships or acquisition interest from major aerospace companies could validate Archer’s technology and provide the additional capital and expertise needed to accelerate commercialization.
International regulatory developments also matter enormously. While Archer pursues FAA certification in the United States, European and Asian regulators are developing parallel certification frameworks for eVTOL operations. Success in multiple geographies could substantially expand addressable markets, but regulatory fragmentation could also delay commercialization and complicate manufacturing strategy. Archer’s ability to navigate these complex regulatory environments will significantly influence its long-term competitive position and investor returns.
Evaluating Risk and Timing
Whether Archer Aviation’s 50% stock decline represents a buying opportunity ultimately depends on individual investor risk tolerance, investment time horizon, and conviction in the broader eVTOL thesis. The company remains pre-revenue, making traditional valuation metrics largely irrelevant. Investment decisions must be based on qualitative assessments of technology, regulatory progress, competitive positioning, and capital efficiency—factors where reasonable investors can disagree substantially.
Risk-averse investors might reasonably conclude that waiting for more definitive proof of regulatory approval and customer demand represents a prudent approach. The company’s stock could easily fall further if commercialization timelines extend or regulatory hurdles prove more challenging than anticipated. Conversely, more aggressive investors with high risk tolerance might view the current valuation as having already incorporated significant downside scenarios and see asymmetric upside potential if Archer successfully executes on its stated roadmap.
Market history suggests that early-stage companies in transformative technology sectors frequently see extreme stock volatility, with substantial recoveries following periods of pessimism. The question for individual investors is whether they have sufficient confidence in Archer’s technology, leadership, and market opportunity to weather potential additional declines while waiting for commercialization validation. For many investors, the honest answer may be that the risk profile is simply incompatible with their investment objectives, regardless of the potential upside return.
Key Considerations for Potential Investors
- Monitor Archer Aviation’s quarterly regulatory updates and FAA certification progress closely—these milestones will be primary drivers of future stock performance and market sentiment.
- Assess your personal investment time horizon realistically; Archer likely requires 5-10 years before generating meaningful commercial revenue, making it unsuitable for near-term capital needs.
- Diversify eVTOL exposure across multiple companies rather than concentrating in Archer alone, as sector dynamics and regulatory decisions affect all participants but with varying intensities.
- Stay informed about developments in battery technology, electric propulsion systems, and alternative air mobility solutions that could supersede current eVTOL designs.
- Consider your conviction level in urban air mobility’s viability; if you harbor fundamental doubts about the market’s existence or timing, eVTOL stocks may not align with your investment thesis regardless of valuation.
Archer Aviation’s 50% stock decline represents a genuine market repricing of the company’s risk-reward profile, reflecting both sector-wide headwinds and legitimate questions about the path to profitable operations. Whether this creates a buying opportunity or signals deeper trouble remains uncertain—a reality that explains the intense disagreement among sophisticated investors and analysts. The company’s execution over the next 24 to 36 months will likely provide much clearer signals about whether current valuations represent bargains or value traps.