HIGHLIGHTS
- eVTOL manufacturers including Joby Aviation, Lilium, and Archer Aviation are on track for FAA type certification within 18-36 months, unlocking commercial operations
- Boeing, Airbus, and regional aerospace manufacturers have launched eVTOL programs or acquired startups, providing industry validation and substantial capital infusions
- Global urban air mobility market projected to exceed $10 billion annually by 2035, with early investor positioning critical for life-changing returns
The electric vertical takeoff and landing (eVTOL) industry stands at an inflection point, with stock analysts and industry experts increasingly confident that early investors could see life-changing returns as the sector moves from development into full commercial operations. With regulatory frameworks solidifying, manufacturing partnerships expanding, and first commercial routes nearing launch, the eVTOL market is positioning itself as one of the most promising growth opportunities in the mobility and aerospace sectors for the coming decade.
The Investment Thesis Behind eVTOL Growth
The fundamental case for eVTOL stocks rests on several converging factors that are accelerating market maturation. The global urban air mobility market is projected to reach multi-billion dollar valuations within the next 5-10 years, driven by chronic congestion in major metropolitan areas and the proven demand for premium mobility solutions. Early investors who position themselves now stand to benefit from the first-mover advantage as companies achieve regulatory certification and begin revenue-generating operations.
Key drivers of this investment thesis include the dramatic reduction in battery costs, which have fallen by over 80% in the past decade and continue to decline. This technological progression directly improves eVTOL economics, making shorter routes economically viable and reducing operational costs. Additionally, the convergence of autonomous flight technology, advanced materials, and electric propulsion has solved many of the technical hurdles that plagued earlier generations of aircraft development.
Major aerospace manufacturers including Boeing, Airbus, and regional players have either launched their own eVTOL programs or acquired promising startups, providing industry validation and substantial capital infusions. This influx of both institutional capital and manufacturing expertise has accelerated development timelines and increased confidence in near-term commercialization targets.
Regulatory Pathways and Certification Milestones
One of the most significant tailwinds for eVTOL investment is the crystallization of regulatory frameworks across major markets. The U.S. Federal Aviation Administration (FAA), European Union Aviation Safety Agency (EASA), and aviation authorities in Asia-Pacific regions have all published certification pathways specific to eVTOL aircraft. These frameworks provide companies with clear technical requirements and timelines, reducing uncertainty that previously plagued the sector.
Several leading manufacturers are on track to achieve type certification within 18-36 months, which would unlock the ability to begin commercial operations. Companies like Joby Aviation, Lilium, and Archer Aviation have all announced detailed certification schedules with specific milestones. The achievement of these certifications will represent a watershed moment for investor confidence, as it validates that the technology is safe, reliable, and ready for commercial deployment.
Beyond aircraft certification, regulatory agencies are also establishing airspace management systems and operational rules for urban air mobility networks. Cities including Los Angeles, San Francisco, and Singapore have been designated as early testing and operational hubs, providing real-world data that informs broader regulatory policy. This collaborative approach between manufacturers, regulators, and city planners is accelerating the maturation of the entire ecosystem.
Manufacturing Partnerships and Production Capacity
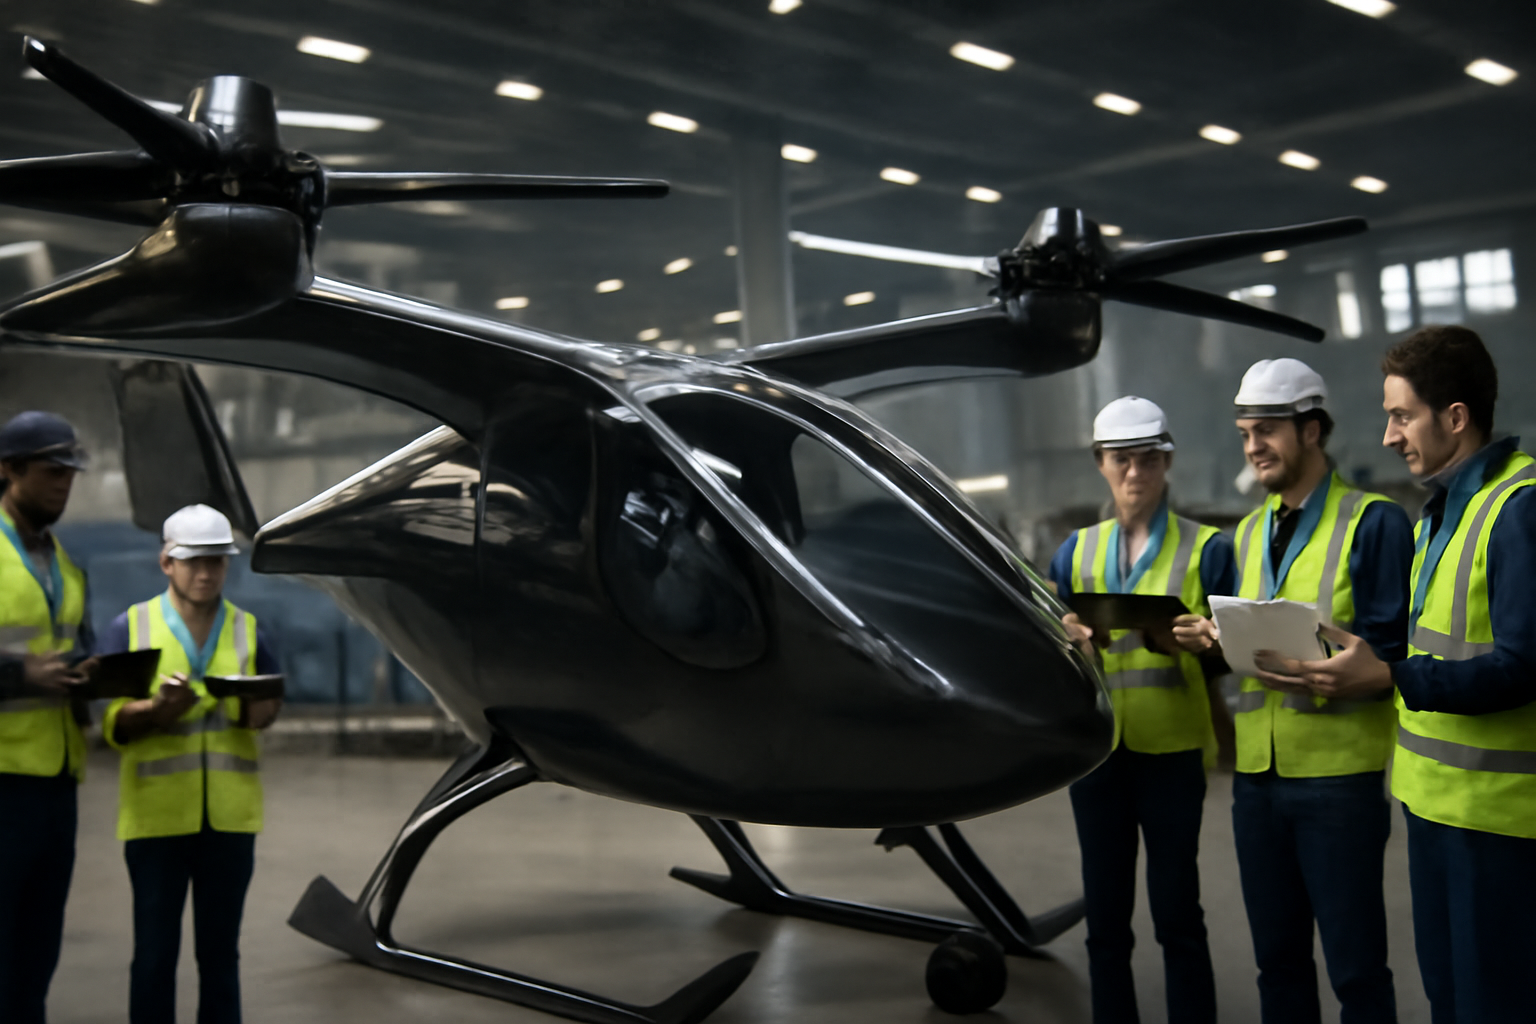
The shift from prototype-focused R&D to scaled manufacturing is underway across the eVTOL industry. Traditional aerospace suppliers including Collins Aerospace, Honeywell, and Safran have signed supply agreements and manufacturing partnerships with leading eVTOL makers, ensuring that production quality meets aviation standards. These partnerships also provide access to global supply chains and manufacturing expertise that would take years to develop independently.
Several manufacturers have secured significant manufacturing facilities or announced joint ventures with established OEMs to scale production capacity. Lilium has partnered with major manufacturers in Europe and Asia, while Joby has secured production partnerships and facility commitments in the United States. These arrangements demonstrate serious capital commitment and production readiness beyond the typical startup development phase.
The economics of eVTOL operations are becoming increasingly favorable as production scales and supply chain efficiencies improve. Manufacturers are targeting production costs that would enable profitable operations at price points competitive with premium ground transportation and helicopter charters. This cost trajectory is critical to sustaining demand during the crucial early years of commercial operation.
Emerging Market Opportunities and Geographic Expansion
While the United States and Europe dominate current eVTOL development, emerging markets in Asia-Pacific, Middle East, and Latin America represent enormous untapped opportunities. Cities like Dubai, Singapore, Seoul, and São Paulo have announced ambitious urban air mobility initiatives and have begun certification planning with local regulators. These markets represent potentially higher-growth opportunities compared to already-congested Western markets.
China’s approach to eVTOL development emphasizes rapid commercialization and domestic champion creation, with several Chinese manufacturers advancing rapidly on parallel timelines to Western competitors. This competitive dynamic is accelerating innovation across the industry and expanding the total addressable market for eVTOL services and infrastructure providers.
Tourism and leisure applications in emerging markets could drive initial demand surges, particularly in island nations and mountainous regions where eVTOL services offer compelling advantages over traditional infrastructure. Companies positioning themselves for these geographic opportunities could capture outsized returns as new markets open for commercial operations.
Key Takeaways for Investors
Critical Investment Insights
- eVTOL regulatory certifications are expected within 18-36 months, marking the transition from R&D to revenue-generating commercial operations
- Manufacturing partnerships with aerospace giants and established supply chain integration significantly reduce production risk and demonstrate serious commercialization commitment
- Global urban air mobility market projections exceed $10 billion annually by 2035, with early investors positioned to capture outsized returns as the sector scales
The eVTOL sector represents a rare convergence of technological maturity, regulatory clarity, manufacturing readiness, and market demand. For early investors who correctly identify companies positioned to achieve commercial success, the potential returns could be substantial. However, as with any emerging technology sector, success requires careful due diligence on individual companies’ technical progress, regulatory status, and financial runway. The next 18-24 months will prove decisive in separating industry leaders from those unable to execute on commercialization promises.