HIGHLIGHTS
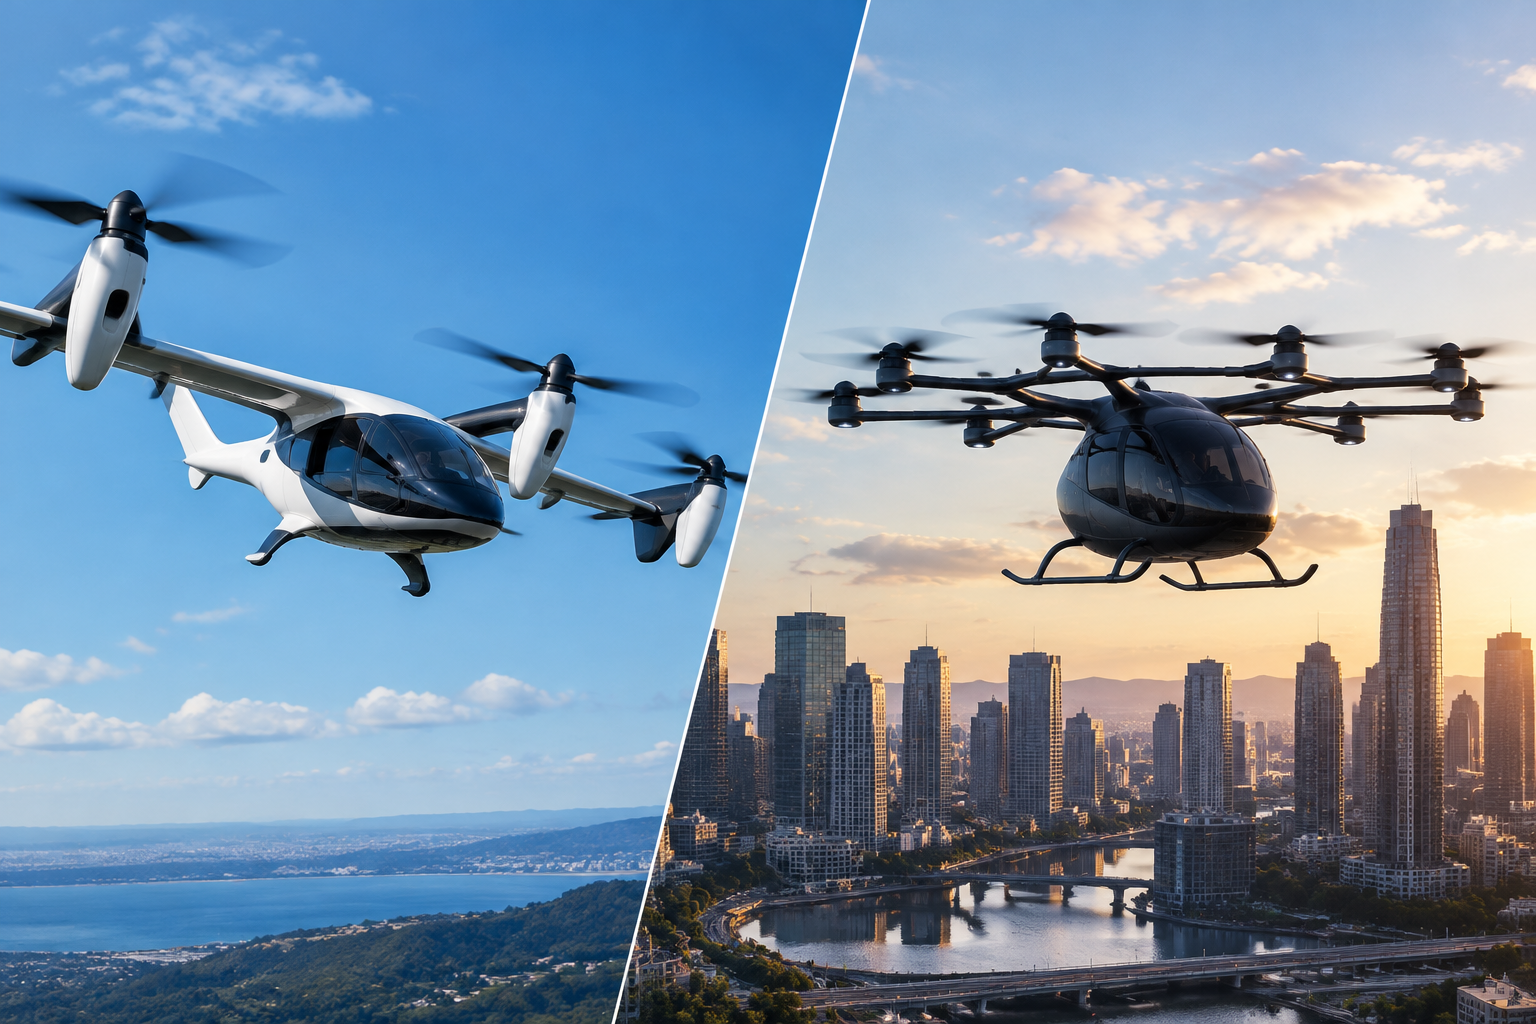
- Joby’s tilting-wing design prioritizes range and efficiency, while Archer’s multicopter approach emphasizes manufacturing speed and simplified certification
- Joby targets premium, long-distance urban air mobility; Archer pursues scalable, volume-driven city services with lower operational costs
- Both companies secured substantial SPAC funding, but face critical challenges achieving profitability as development costs remain high and near-term revenue remains uncertain
The urban air mobility market is heating up as two companies—Joby Aviation and Archer Aviation—position themselves as frontrunners in the eVTOL revolution. While both firms aim to transform personal air travel, their strategic approaches, technological designs, and go-to-market timelines reveal significant differences that could shape the future of aerial transportation. As investors and regulators watch closely, understanding the competitive dynamics between these leaders offers critical insights into where the industry is headed.
Technology and Aircraft Design: Two Different Philosophies
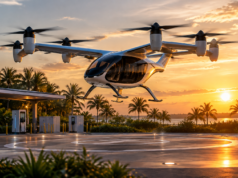
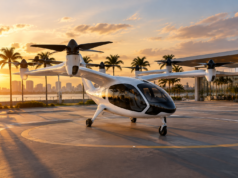
Joby Aviation has invested heavily in a distinctive vertical-takeoff-and-landing (VTOL) design that prioritizes efficiency and passenger comfort. The company’s aircraft features a tilting-wing configuration that enables smooth transitions between hover and cruise flight, reducing energy consumption during long-distance operations. This engineering philosophy reflects Joby’s focus on commercial viability and operational range, key factors for profitable routes.
Archer Aviation, by contrast, has pursued a more conventional multicopter-inspired design with electric propulsion across distributed rotors. This approach simplifies manufacturing and regulatory certification while potentially reducing development timelines. Archer’s design emphasizes rapid scalability and cost-effective production, aligning with the company’s aggressive timeline for commercial operations.
Both approaches have merit, but they reveal divergent priorities: Joby prioritizes long-term efficiency and range, while Archer emphasizes near-term manufacturability and speed to market. These technological differences will likely influence which company captures the early adopter segment and sustains competitive advantage as the industry matures.
Regulatory Strategy and Certification Pathways
Navigating the regulatory landscape is perhaps the greatest challenge facing eVTOL operators. Joby Aviation has taken a collaborative approach with the FAA, working to establish comprehensive certification standards that could benefit the entire industry. The company’s early engagement with regulators demonstrates confidence in its design and operational safety protocols, positioning Joby as a thought leader in industry standards-setting.
Archer Aviation has similarly worked with regulators but appears to be emphasizing a faster path to certification through its design simplicity. The company’s multicopter configuration may require less regulatory precedent than Joby’s novel tilting-wing architecture, potentially accelerating the timeline to Part 135 certification for commercial operations.
These divergent regulatory strategies reflect a fundamental tension in the eVTOL market: should companies prioritize comprehensive, industry-leading standards (Joby’s approach) or pursue the fastest viable certification path (Archer’s strategy)? The answer will depend partly on market demand and the FAA’s willingness to approve novel designs.
Capital Requirements and Financial Sustainability
Both Joby and Archer have secured substantial funding to support development and commercialization. Joby Aviation completed a SPAC merger with Reinvent Technology Partners, raising significant capital for manufacturing scale-up and operational expansion. This influx of funding enabled the company to advance its aircraft development and explore strategic partnerships with ride-sharing platforms and mobility operators.
Archer Aviation pursued its own SPAC merger with Atlas Crest Investment Corp., securing funds for aircraft testing, factory construction, and regulatory compliance. The company’s financial strategy emphasizes reinvestment in manufacturing infrastructure, signaling confidence in near-term demand for its aircraft.
However, both companies face the challenge of achieving profitability amid rising development costs and uncertain near-term revenue. Capital allocation decisions made today will determine which company can sustain operations through the critical early commercial phase when volumes are low but development costs remain high.
Market Positioning and Route Strategy
Joby Aviation has emphasized premium, long-distance urban air mobility services, targeting routes connecting airports to city centers and inter-city corridors. The company’s partnerships with established transportation operators and tourism platforms suggest a strategy focused on high-value passenger experiences. This positioning allows Joby to command premium pricing while building brand recognition in affluent markets.
Archer Aviation appears to be targeting a broader range of urban mobility use cases, including shorter city-center routes and point-to-point transportation for business travelers. The company’s emphasis on manufacturing scalability suggests intentions to capture volume-driven segments where per-unit costs and operational efficiency become paramount.
These market positioning strategies reflect different views on the eVTOL market’s near-term structure. Joby’s premium approach concentrates risk on high-paying customers willing to accept novel transportation modes, while Archer’s broader strategy aims to serve a larger market segment as prices eventually decline with production scale.
Key Strategic Differences: What Sets Them Apart
- Aircraft Design: Joby’s tilting-wing prioritizes range and efficiency; Archer’s multicopter emphasizes manufacturing speed and regulatory simplicity
- Regulatory Approach: Joby leads industry standard-setting; Archer pursues faster individual certification through simpler design
- Market Strategy: Joby targets premium, long-distance routes; Archer positions for scalable, volume-driven urban mobility services
As the eVTOL industry moves from development to early commercialization, the competition between Joby Aviation and Archer Aviation will shape market expectations, regulatory frameworks, and consumer adoption. Neither company has achieved operational dominance yet, and the outcome will depend on execution, market timing, and unforeseen technical or regulatory developments. Investors, operators, and regulators should monitor both companies closely as their strategic choices ripple across the emerging urban air mobility ecosystem. The winner may not be determined by superior technology alone, but by which company better aligns its design, regulatory strategy, and market positioning with real-world demand.