HIGHLIGHTS
- Battery breakthroughs now enable 100+ km flight ranges, making airport shuttles and inter-city routes commercially viable.
- FAA and EASA have established fast-tracked certification pathways, unlocking a wave of commercial fleet orders from airlines and mobility platforms.
- Global vertiport construction is accelerating through public-private partnerships, with standardized infrastructure now supporting multi-manufacturer competition.
The electric vertical takeoff and landing (eVTOL) industry is experiencing unprecedented momentum as we approach the final months of 2026. While traditional aviation headlines often dominate news cycles, the personal air mobility sector has been quietly revolutionizing transportation infrastructure across major metropolitan areas worldwide. This surge in development reflects growing confidence from investors, regulators, and manufacturers that eVTOL aircraft are transitioning from concept to operational reality.
Regulatory Breakthroughs Drive Market Confidence
Governments around the world have begun establishing clear regulatory frameworks specifically designed for eVTOL operations. These frameworks address critical safety standards, pilot certification requirements, and airspace integration protocols that were previously undefined. The establishment of clear guidelines has eliminated much of the regulatory uncertainty that previously hindered manufacturer confidence and investor backing.
Major aviation authorities, including the FAA and EASA, have fast-tracked certification pathways for leading eVTOL manufacturers. This accelerated approach recognizes the distinct operational profiles of electric aircraft compared to traditional rotorcraft and fixed-wing planes. Certification programs now include specific criteria for battery management systems, autonomy capabilities, and vertiport infrastructure standards.
The regulatory clarity has triggered a cascade of commercial announcements from both established aerospace companies and emerging startups. Airlines, ride-sharing platforms, and logistics operators have begun signing letters of intent for eVTOL fleet acquisitions, signaling genuine market demand beyond venture capital speculation.
Battery Technology Reaches Critical Milestones
Battery performance has historically been the primary technical bottleneck for eVTOL development. Recent breakthroughs in solid-state and lithium-metal battery chemistry have dramatically improved energy density while simultaneously reducing charging times. Current generation batteries now support mission profiles that satisfy the majority of near-term urban air mobility use cases.
Energy density improvements have enabled manufacturers to extend flight ranges from 25 kilometers to over 100 kilometers on a single charge. Extended range capabilities open new operational possibilities, including airport shuttle services, inter-city connections, and emergency medical transport applications. Battery cost reductions have also progressed faster than industry forecasts predicted, improving the economic viability of commercial eVTOL operations.
Supply chain developments support this technical progress. Battery manufacturers have ramped production capacity specifically for aerospace applications, and partnership agreements between automotive, energy, and aerospace companies are creating integrated supply ecosystems. These developments suggest that battery availability will not constrain eVTOL commercialization timelines.
Infrastructure Investment Accelerates Globally
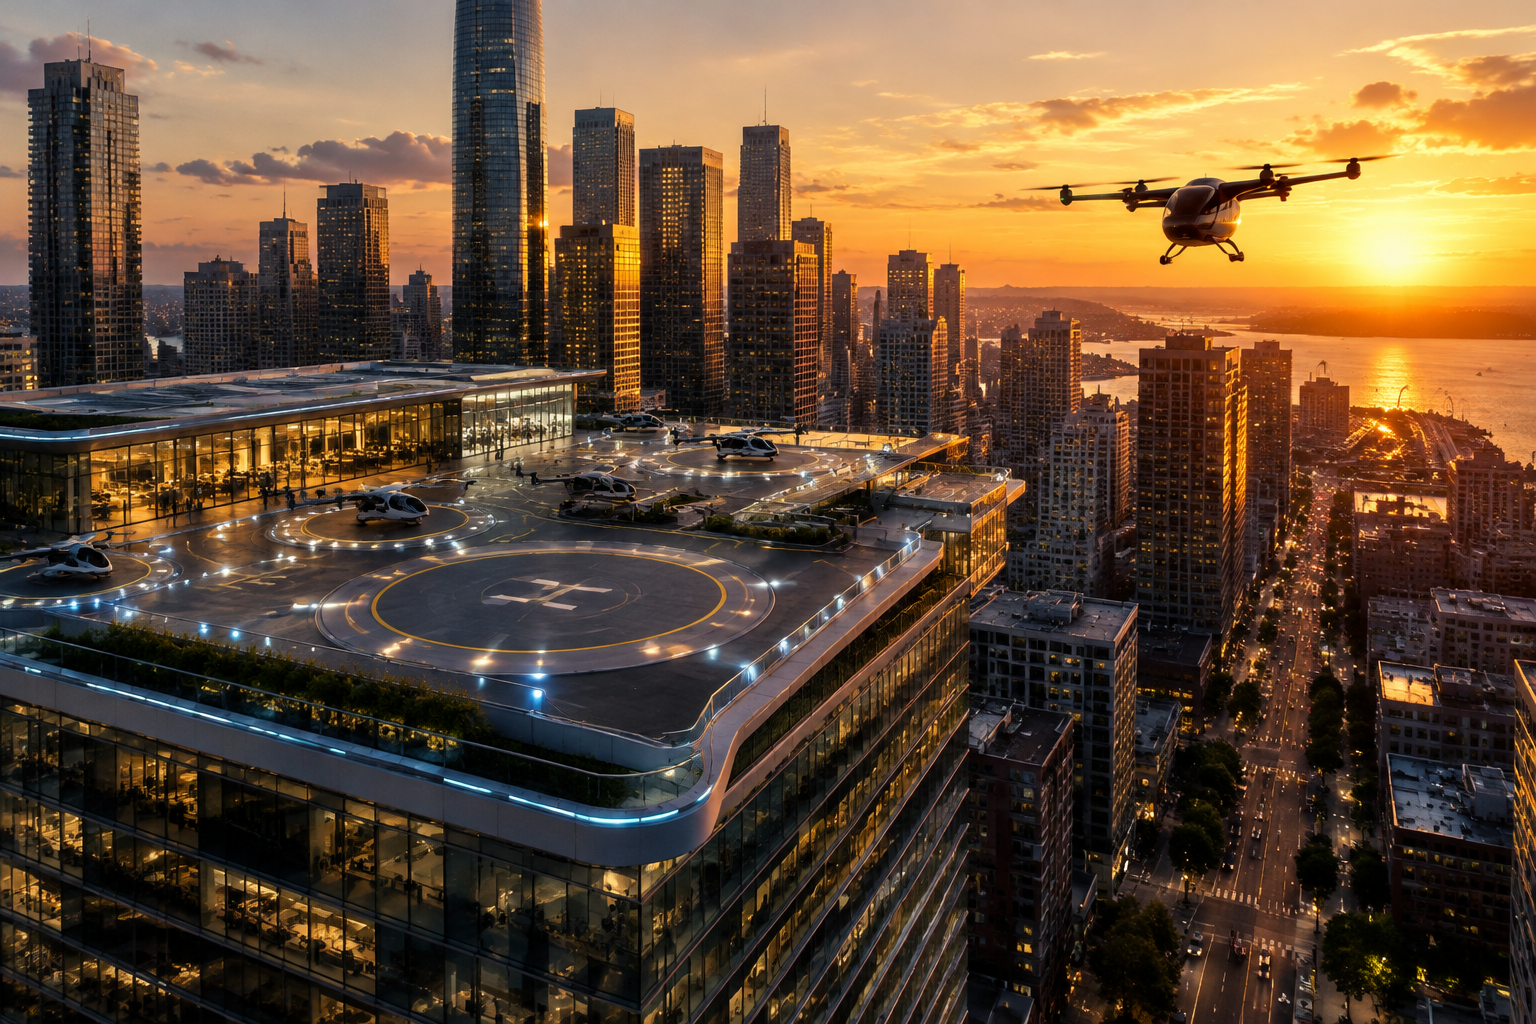
Vertiport development has evolved from theoretical planning to active construction across North America, Europe, and Asia-Pacific regions. Major cities including Los Angeles, London, Tokyo, and Singapore have begun infrastructure projects that will integrate eVTOL landing sites into existing urban transportation networks. These vertiports range from rooftop facilities to ground-level transit hubs designed for seamless passenger transfers.
Public-private partnership models have emerged as the dominant infrastructure development approach. City governments provide regulatory support and real estate access while private operators handle construction, operations, and maintenance responsibilities. This collaborative model has accelerated project timelines significantly compared to purely public-sector infrastructure development models.
Infrastructure standardization initiatives are ensuring that vertiport facilities can accommodate aircraft from multiple manufacturers. Standardized charging interfaces, landing pad dimensions, and ground support equipment will enable competitive service offerings and prevent vendor lock-in scenarios that could constrain market development.
Commercial Service Launches Expand Globally
Several pioneering eVTOL operators have transitioned from pilot programs to regular scheduled service operations. These services initially focus on high-value applications including executive transport, emergency medical response, and premium airport connections. Passenger feedback from initial operations has consistently validated the core value proposition of time savings and convenient urban access.
Ride-sharing platform partnerships represent a significant expansion vector for eVTOL services. Integration with existing consumer-facing mobility applications introduces eVTOL options to mainstream users who previously had no awareness of the technology. Pricing models that reflect premium positioning while remaining competitive with luxury ground transportation are proving attractive to target customer segments.
Cargo and logistics applications are simultaneously developing in parallel to passenger services. Medical specimen delivery, e-commerce parcel distribution, and emergency supply transport represent high-margin applications that can sustain operations during the market development phase. Autonomous cargo aircraft concepts are advancing simultaneously, with several manufacturers conducting flight testing of fully autonomous systems.
Key Industry Takeaways
- Battery technology breakthroughs have extended eVTOL flight ranges beyond 100 kilometers, enabling viable commercial services for airport shuttles and inter-city routes.
- Regulatory frameworks from major aviation authorities have created clear certification pathways, triggering wave of commercial commitments from airlines and mobility platforms.
- Global vertiport infrastructure projects are transitioning from planning phases to active construction, with public-private partnerships accelerating deployment timelines.
The convergence of regulatory clarity, technical maturity, infrastructure investment, and commercial service launches suggests that personal air mobility is transitioning into a genuine market phase. Industry participants from startup manufacturers to established aerospace companies are positioning themselves for sustained growth. While challenges remain—particularly regarding noise mitigation, energy efficiency optimization, and public acceptance—the trajectory strongly indicates that eVTOL aircraft will become a visible component of urban transportation networks within the next two to three years. Stakeholders who establish market positions during this critical development window will likely secure significant competitive advantages as the industry scales toward mainstream adoption.