HIGHLIGHTS
- Mass-market flying cars won’t arrive until the 2040s at earliest, contradicting industry promises of 2025-2027 timelines.
- Cities lack vertiports, airspace management systems, and zoning approval for widespread eVTOL infrastructure deployment.
- Current eVTOL costs ($250K-$1M+) and operating expenses ($200-500 per trip) make personal flying cars economically impractical for mainstream consumers.
The dream of owning a flying car has captivated human imagination for decades, fueling countless movies, television shows, and science fiction novels. Yet despite remarkable technological advances in electric vertical takeoff and landing (eVTOL) aircraft, the reality of a personal aerial vehicle parked in your garage remains firmly in the realm of fantasy. A recent investigation by KSL News exposes the vast gap between industry hype and practical implementation, revealing that widespread adoption of flying cars is still many years—if not decades—away.
The Timeline Reality Check
Industry optimists have repeatedly promised that flying cars would revolutionize urban transportation within the next 5-10 years. From major manufacturers to startup ventures, companies have consistently projected near-term deployment of commercial eVTOL services in major metropolitan areas. However, KSL’s deep dive into current progress reveals a more sobering reality: regulatory approval, infrastructure development, and technical hurdles remain formidable obstacles that continue to push realistic deployment timelines further into the future.
The original promises from the early 2020s have largely failed to materialize. What was once billed as a 2025-2027 revolution in urban air mobility has now shifted to projected timelines of 2030 and beyond for limited commercial operations. For mass-market adoption—where flying cars might actually be available for everyday consumers—realistic estimates now extend well into the 2040s or later, assuming everything proceeds according to plan with no further setbacks.
This pattern of delay reflects the complexity of transitioning from prototype and demonstration flights to certified, commercial operations at scale. The regulatory environment alone requires extensive safety testing, airspace management protocols, and insurance frameworks that simply do not yet exist. Each new challenge discovered during testing adds months or years to the timeline, pushing consumer availability further down the road.
Regulatory and Safety Barriers
One of the most significant obstacles preventing flying cars from entering your garage is the regulatory approval process. Aviation authorities worldwide, including the FAA in the United States, have established rigorous certification standards that eVTOL aircraft must meet before they can carry passengers commercially. These standards were developed for traditional helicopters and fixed-wing aircraft, and adapting them for dozens of new electric vertical takeoff designs requires extensive testing and validation.
Safety remains the paramount concern for regulators who understand that any fatal accident involving a commercial eVTOL service could derail public confidence in the technology for years. This cautious approach, while sometimes frustrating for industry enthusiasts, reflects lessons learned from previous transportation revolutions. The regulatory bodies are tasked with protecting the public, which means every new aircraft design, operational procedure, and safety system must be thoroughly vetted before approval.
Beyond certification, there are questions about who bears responsibility in case of accidents, how insurance premiums will be calculated, and what liability protections manufacturers need. These legal and insurance frameworks are still being negotiated and developed, adding another layer of complexity to the path toward commercial operations. Until these questions are resolved, manufacturers remain hesitant to commit to aggressive commercialization timelines.
Infrastructure and Urban Air Mobility Challenges
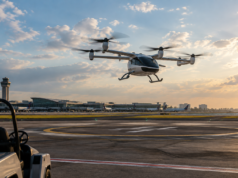
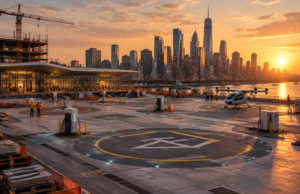
Even if flying cars were available tomorrow, the infrastructure required to support them doesn’t exist. Unlike traditional automobiles that can operate from any paved road, eVTOL aircraft require designated vertiports—specialized facilities equipped to handle takeoffs, landings, battery charging, maintenance, and passenger processing. Building a network of vertiports across a single major city, let alone an entire country, represents an enormous capital investment and coordination challenge.
Cities must also establish airspace management systems capable of safely coordinating hundreds or thousands of eVTOL flights per day. This requires sophisticated air traffic control systems, communication protocols, and collision avoidance technology that are still in development. Urban airspace is far more constrained and complex than traditional aviation corridors, requiring entirely new approaches to managing traffic flow, routing, and emergency procedures.
Noise pollution and environmental concerns further complicate the infrastructure picture. While eVTOL aircraft are electric and therefore less polluting than traditional helicopters, they still produce significant noise during takeoff and landing. Communities living near proposed vertiport locations have already begun raising objections, suggesting that public acceptance—and zoning approval—may prove more difficult than some optimists anticipated.
Technical Development and Performance Limitations
Current eVTOL prototypes face significant technical challenges that remain unsolved. Battery technology, while improving rapidly, still limits flight range and payload capacity compared to what many operational scenarios demand. A typical eVTOL aircraft might offer a range of 20-50 miles on a single charge, which works for specific point-to-point routes but doesn’t provide the flexibility that personal car ownership offers. Battery degradation over time and the need for frequent recharging further limit practical utility.
Passenger capacity also remains constrained. Most current eVTOL designs carry between two and six passengers, compared to the five to eight seats typical of a conventional car. This limitation means that flying cars would primarily serve as premium transportation for high-value trips rather than replacing everyday vehicles for most people. The operating costs per passenger remain extremely high—early estimates suggest $200-500 per trip in urban air mobility services—making frequent personal use economically impractical for average consumers.
Manufacturing scalability presents another technical hurdle. Moving from building dozens of prototype aircraft to manufacturing thousands of commercial units requires entirely new production facilities, supply chains, and workforce training. No eVTOL manufacturer has yet demonstrated the ability to scale production to the volumes needed for mass-market adoption, and doing so while maintaining safety and quality standards remains an open question.
Economic and Consumer Adoption Realities
Key Takeaways
- Flying cars face regulatory, infrastructure, and technical barriers that push realistic mass-market availability to 2040s or beyond, not the 2025-2027 timelines originally promised by manufacturers.
- eVTOL aircraft require expensive specialized vertiports, sophisticated urban airspace management systems, and noise mitigation solutions that most cities have not yet begun building.
- Current battery technology, limited passenger capacity (2-6 seats), and estimated operating costs of $200-500 per trip make flying cars economically impractical for everyday consumer use in the foreseeable future.
Even if all technical and regulatory hurdles were somehow overcome tomorrow, the economic model for consumer flying cars remains questionable. Purchasing price projections for production aircraft suggest costs ranging from $250,000 to $1 million or more per vehicle, placing them far beyond the reach of ordinary consumers. This price point is comparable to luxury sports cars or small helicopters, positioning flying cars as ultra-premium assets rather than mainstream transportation options.
Operating costs would be equally prohibitive. Maintenance, battery replacement, insurance, and landing fees would make regular use economically inefficient compared to existing ground transportation options. For most people, even wealthy individuals, traditional cars, public transit, and occasional helicopter or jet charter services offer better value and convenience than owning a personal flying vehicle. Until eVTOL technology can dramatically reduce both purchase and operating costs, adoption will remain limited to niche applications.
The Path Forward: A Measured Perspective
The takeaway from KSL’s investigation and broader industry analysis is that flying cars will not revolutionize transportation in the next five or ten years. More realistic expectations suggest that limited commercial eVTOL services may emerge in a few major cities by 2030-2032, serving premium point-to-point routes and wealthy passengers. Mass adoption—if it ever occurs—likely extends decades further into the future, contingent on breakthroughs in battery technology, significant cost reductions, and resolution of complex regulatory and infrastructure challenges.
This doesn’t mean the industry should be dismissed or that investment should stop. eVTOL technology has genuine potential for specific applications, including emergency medical transport, cargo delivery, and premium urban mobility services. However, it’s crucial to separate realistic near-term applications from long-term aspirations and to acknowledge the substantial work remaining before flying cars become a practical consumer product.
The flying car remains an exciting frontier of transportation technology, but managing expectations is essential. When someone asks “when will there be a flying car in your garage?” the honest answer is: not anytime soon. The dream persists, but the timeline remains measured in decades, not years. As technology continues to advance and regulatory frameworks develop, perhaps one day the flying car will finally transition from science fiction to everyday reality—but that day is still far more distant than early industry optimism suggested.